
Drone insurance cost depends on the equipment, the work being performed and the cover selected. A photography business using one compact drone has a different insurance profile from a fleet carrying specialist sensors or spraying crops.
Before comparing premiums, decide which losses you want to insure and describe the operation accurately. This guide explains the questions behind a quote; the ABS drone insurance page provides an overview of the cover options.
For a related check, read the difference between drone public liability and hull cover.
Discuss your drone, pilots, work and insurance questions with ABS Insurance Brokers.
Bring your equipment list and operating details so the proposed cover can be reviewed.
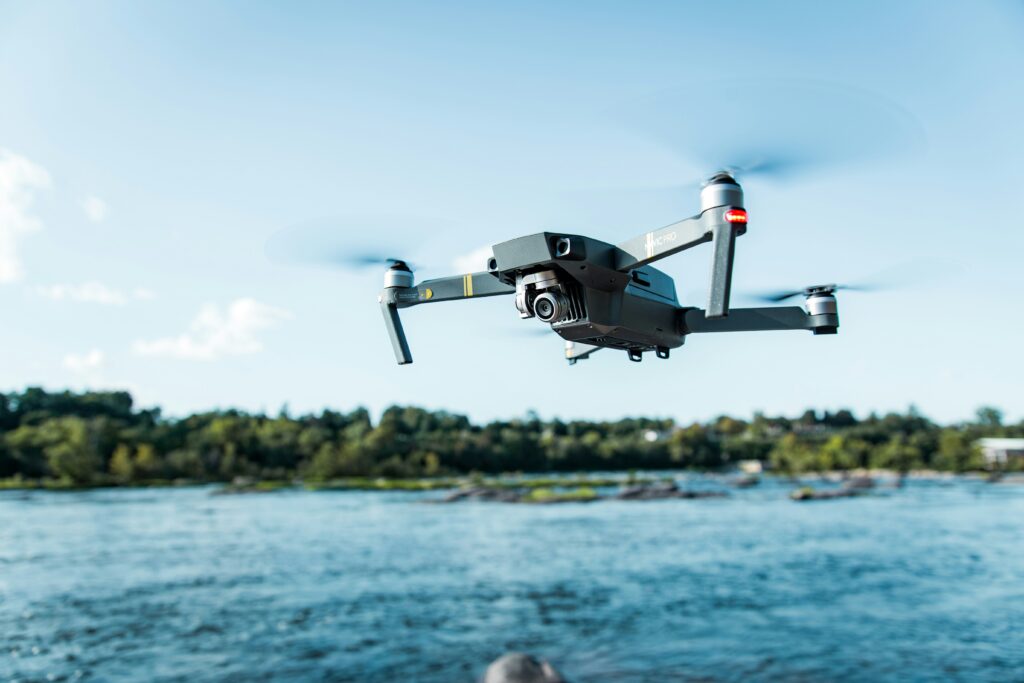
A useful quote starts with your business, rather than a headline premium. The insurer needs to understand what could be damaged, who could be injured and the activities it is being asked to accept. A price for equipment alone cannot be compared directly with a policy including aviation liability.
There is no universal premium or minimum liability limit that suits every Australian operator. Your client’s contract may also set requirements. Ask for a written breakdown of the premium, taxes, duties, broker fees and any instalment costs so that you compare the total payable.
Tell the broker about planned work as well as current jobs. A cheaper quote based on an incomplete description is a poor foundation for a new contract.
Physical damage cover concerns your insured drone and listed equipment. Aviation liability concerns specified legal liabilities to others. A broken camera and a claim from a neighbouring property owner are different losses, even when caused by the same flight.
QBE’s RPAS product overview is one example of an insurer describing separate equipment and liability sections. It is not a promise that every drone policy includes the same benefits. Ask which sections, limits and conditions are actually included in your quotation.
The commercial drone insurance guide explains how these cover decisions relate to the wider operation.
Give each quoting provider the same aircraft schedule, values and operating description. Then compare the insured entity, covered activities, territory, pilots, liability limit, settlement basis and excesses. Ask whether payloads, hired equipment, theft and transit are included or need separate agreement.
Check how an excess applies: a fixed amount and a percentage can produce very different out-of-pocket costs. Also ask what happens when one incident damages multiple insured items. A higher excess may change the premium, but only accept an amount the business could realistically fund.
Do not assume lost bookings, replacement hire or data recovery follow automatically from equipment cover. Request a clear answer for each exposure that matters to the business.
CASA registration and operating requirements are separate from insurance pricing. Check CASA’s drone registration requirements and supply accurate details. Before changing an existing policy, ask the broker to confirm the new arrangements and any remaining conditions in writing.
A lower equipment value may affect the physical damage premium, but it does not describe the liability exposure. The type of work, cover limits and policy terms still matter.
Ask whether a liability-only quotation is available for your operation. It leaves the cost of damage to your own drone with you unless another policy responds. Compare that retained risk before deciding.
No. Check the plan’s terms separately. A repair or replacement arrangement should not be assumed to provide aviation liability, theft cover or cover for your complete commercial operation.
No. Training and documented procedures help explain the risk, but pricing and eligibility remain underwriting decisions. There is no guaranteed discount.
Send ABS your equipment schedule, operating description, pilot information and required limits. Ask for the scope of cover and the total payable, rather than comparing a premium in isolation.
Send ABS your equipment values, services and contract requirements. We can help you compare the proposed cover and identify questions to resolve before you arrange insurance.
General information: This article does not take account of your objectives, financial situation or needs. Cover is subject to underwriting, the policy wording, schedule, endorsements, limits, excesses and exclusions. Read the relevant documents and seek advice appropriate to your circumstances. Check current regulatory requirements with the relevant authority.
