General Liability Insurance for Tradies: Australian Guide
General liability insurance helps tradies manage legal liability for injury to other people or damage to their property. In Australia, policies often use the terms public liability or public and products liability. Check the wording, limits and exclusions to see how the cover applies to your trade.
A dropped tool can damage a client’s car. A visitor can trip over materials. An installed product can cause damage after a job ends. These examples involve different facts, so no policy name alone confirms that a claim is covered.
What general liability insurance can cover
A public liability policy may pay compensation for covered claims arising from your business activities. It may also cover approved defence costs. The policy determines the trigger, insured parties, excess and conditions, including when the insurer must approve legal expenses.
- Third-party injury: claims involving clients, visitors or members of the public.
- Third-party property damage: accidental damage to someone else’s property arising from covered business activities.
- Products liability: liability arising from products supplied or installed, where that section is included.
- Defence costs: legal expenses covered on the terms set out in the policy.
Public liability does not automatically pay to repair faulty workmanship itself. Exclusions for the property you are working on, contractual liabilities or particular activities can also affect a claim. Ask how those clauses apply to the jobs you accept.
General liability and public liability: compare the wording
Insurers can use different labels for similar liability products. A public and products liability policy may combine two sections, while another product may provide a narrower scope. Compare the insuring clauses and definitions, rather than assuming every use of “general liability” means identical cover.
| Cover | Risk to discuss | Key check |
|---|---|---|
| Public liability | Injury or property damage involving third parties | Declared activities, exclusions and defence costs |
| Products liability | Injury or damage connected with supplied products | Included products, territories and aggregate limits |
| Professional indemnity | Claims arising from professional advice or services | Professional activities and notification requirements |
| Tools and plant cover | Loss of or damage to your own equipment | Insured items, locations, theft conditions and excesses |
Who should consider general liability insurance?
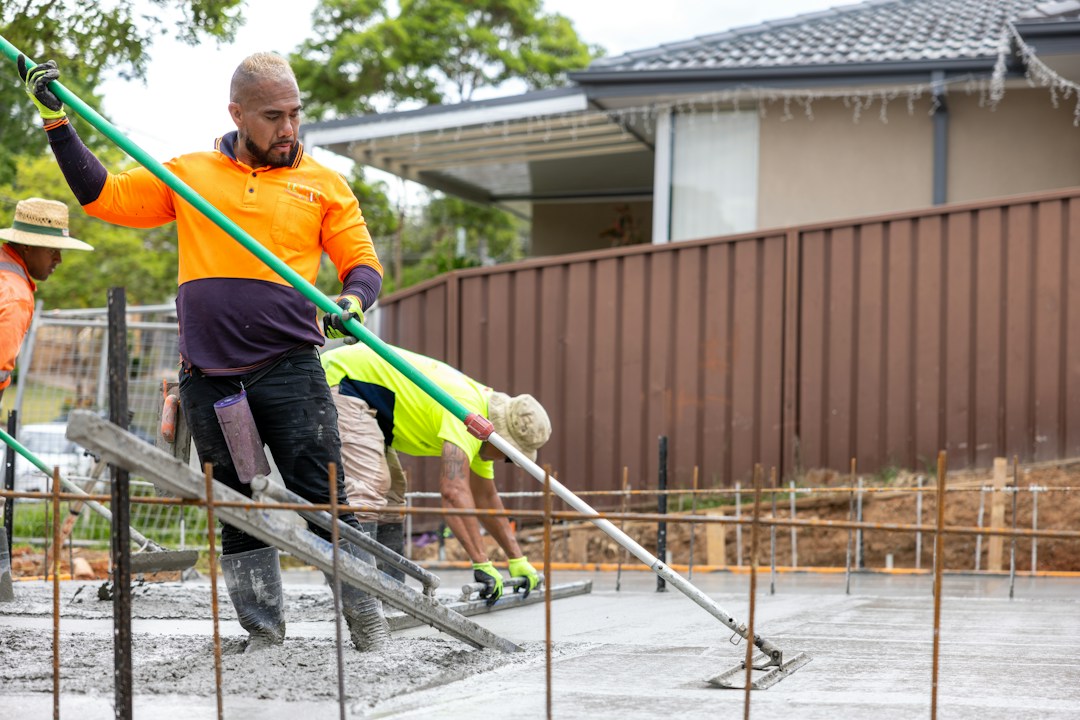
Builders, carpenters, electricians, plumbers and other contractors work around people and property they do not control. Even a small business can face a large claim. Review your activities, job locations and contracts before choosing a policy.
Tell your broker about subcontractors, work at height, hot work, demolition, excavation or other specialist activities. Also declare changes during the year. A certificate of currency confirms cover exists at a point in time; it does not explain every exclusion or extension.
General liability insurance limits and related cover
Choose a limit by considering your contracts and the potential size of a claim. Ask whether a limit applies to each occurrence or across the policy period. Check products liability aggregates, sub-limits and the treatment of defence costs.
A lower premium can reflect a higher excess or a narrower policy. Compare equivalent limits and declared activities before judging price. Keep written confirmation of any extension needed for a particular job.
Professional advice or design can create exposures that need professional indemnity cover. Your own equipment may need tools insurance or plant and machinery insurance. Workers compensation and contract works cover address separate risks.
For a broader review, explore ABS tradies insurance and our public liability insurance service.
Official Australian guidance on liability cover
The Australian Government’s public liability guidance describes cover for death, injury or property damage caused by a business’s negligence. The policy schedule and wording determine the actual insured events, limits, exclusions, excess and treatment of legal costs. Check the rule for your occupation and state or territory, then compare the wording with your contracts and the work you perform.
What to check before you take out a policy
- The activities and trades listed on the schedule, and whether they match the work you actually take on
- The limit of liability, and whether any sub-limits apply to particular claim types
- The exclusions, and how they interact with the way you work
- The excess you would pay if a claim were made against you
- Whether products liability sits alongside your public liability cover
- Whether the policy responds to legal costs, and on what terms
- Whether you need separate professional cover for advice or design work
- The claims notification process and who you contact when something goes wrong
Working with a broker on liability cover
ABS Insurance Brokers Pty Ltd is an Australian-owned brokerage based at Bankstown Airport in Sydney, NSW. The business arranges specialist business, construction, aviation and commercial insurance for Australian businesses, alongside adjacent services including developer finance and building consultancy. For tradies and contractors, the practical value of a broker sits in matching the policy schedule to the work you actually do, checking the exclusions that catch trades, and keeping the cover current as the business grows or changes direction. The brokerage draws on more than 100 years of combined experience across its team.
Because general liability and public liability wording varies between insurers, it helps to have someone read the policy against your real scope of work instead of the headline product name. Bring your contract requirements, your subcontractor arrangements and a plain description of the jobs you take on, then ask how each element of the policy responds to each of those situations.
Frequently Asked Questions
Is general liability insurance the same as public liability insurance in Australia?
The labels can overlap, but policies are not automatically identical. Public and products liability may be combined, and definitions differ. Compare the insuring clauses, exclusions and limits before relying on the product name.
How much does business general liability insurance cost?
There is no single premium that applies to every tradie. Insurers assess the business, including its trade activities, turnover, claims history, subcontracting arrangements, selected liability limit and excess. Provide an accurate description of the work you perform when requesting quotes, then compare exclusions and limits as well as price.
Is public liability insurance compulsory for tradies in Australia?
Some states and territories require public liability insurance for certain occupations. Check the rules for your trade and location with the relevant regulator. Contracts, site rules and client requirements may also require cover, so confirm the limits and wording before you start work.
How much cover should a contractor take out?
Match the limit to your contracts, activities and potential claims. Ask whether it applies per occurrence or in the aggregate, and check sub-limits and defence costs. Your broker can compare suitable options for your work.
Does general liability insurance cover legal costs?
Whether legal defence costs are covered, how they are managed, and whether they reduce the policy limit depends on the wording. Check the claims and legal-cost clauses, including any insurer consent requirements, and ask your broker to explain how they apply before you rely on the cover.