Professional indemnity insurance pays investigation costs, defence costs and compensation when a client alleges that advice, design or other professional work caused a financial loss.
You're completing a tender schedule when the principal asks for evidence of PI cover. You already have public liability and contract works insurance, but your scope also includes shop drawings, technical recommendations or responsibility for a consultant's design. The important question isn't whether you have another certificate of currency. It's whether the policy covers the professional work you've agreed to deliver, including work from completed jobs.
Table of Contents
- What Professional Indemnity Insurance Pays For
- PI Compared with Public Liability and Management Liability
- Who Needs PI on a Building Job
- How a Claims-Made PI Policy Responds
- Limits and Exclusions That Change the Outcome
- Claim Stories from Design Advice and Instructions
- Arrange Professional Indemnity Cover Before You Tender
What Professional Indemnity Insurance Pays For
Professional indemnity insurance is liability cover for allegations that advice, design, specifications, certification, estimates or other professional work caused a client financial loss. Subject to the wording, it may pay for investigating the allegation, appointing solicitors, defending the claim and paying a covered settlement or damages.
Say a designer issues an incorrect drainage detail for a retaining wall. After a wet season, the wall moves, and the owner demands rectification costs and lost rent while the adjoining premises are unavailable. Nobody has been injured, but the owner still alleges a substantial financial loss caused by professional work.
That's a PI exposure, although the wall's physical damage means other policies may also need examination. No injury doesn't automatically rule out public liability, because public liability can cover property damage too. The allegation, damaged property and policy exclusions determine which insurer needs notification.
Financial loss without an accident
The distinction becomes clearer when the error causes no physical damage at all. An incorrect specification might require an owner to replace an unsuitable product before installation, or a faulty estimate might lead a principal to make an expensive procurement decision.
Pure financial loss means economic loss that doesn't result from bodily injury or physical property damage. It's a central reason construction businesses assess PI separately from their site-based insurance.
Practical rule: Ask what professional decision the client relied on, not just what happened on site.
Australia has an established supervisory framework for these risks: APRA's National Claims and Policies Database records PI and public and product liability policy and claims information from APRA-regulated general insurers, covering business underwritten since 2003.
Where the requirement appears
Construction firms commonly encounter PI requirements in:
- Design-and-construct contracts, where the builder accepts responsibility for design.
- Consultant deeds and tender schedules, which describe required insurance and professional services.
- Registration and principal requirements, particularly for technical and advisory roles.
A trade contractor who only installs plasterboard to someone else's drawings has a different exposure from a subcontractor who prepares design details or certifies compliance. The trade name alone doesn't answer whether PI is appropriate.
For anyone asking “what is professional indemnity insurance?”, the useful answer is practical: it protects against covered allegations about professional judgement, not accidents during construction.
PI Compared with Public Liability and Management Liability
| Question | Professional indemnity | Public liability | Management liability |
|---|---|---|---|
| What triggers it | Allegation of negligent advice, design, certification or breach of professional duty | Third-party bodily injury or property damage from business operations | Wrongful management act, employment practices allegation or specified crime |
| Typical loss | Client financial loss, rectification tied to professional error, and defence costs | Injury, property damage and sometimes product liability | Liability of the company or its directors and officers; specified company losses |
| Usual claimant | Client, principal or another party who relied on the professional work | Member of the public, neighbour, visitor or property owner | Employees, regulators, shareholders or the company, according to the section |
| Policy basis | Usually claims-made and notified, with a retroactive date | Usually occurrence-based, linked to when the incident happens | Usually claims-made for management sections; crime sections have separate triggers |
| Construction example | Undersized beam, missed certification or a negligent estimate | Debris striking a car or a visitor injured on site | Unfair dismissal claim or an alleged misleading statement by a director |
| Does not cover | Not a substitute for public liability or contract works | Generally excludes negligent advice and pure financial loss | Not a substitute for design-error or site-injury cover |
Choose the column by the allegation, not by the premium or the policy with the largest headline limit. These are typical distinctions, not promises that every policy uses identical wording.
The visual comparison highlights the different starting points.
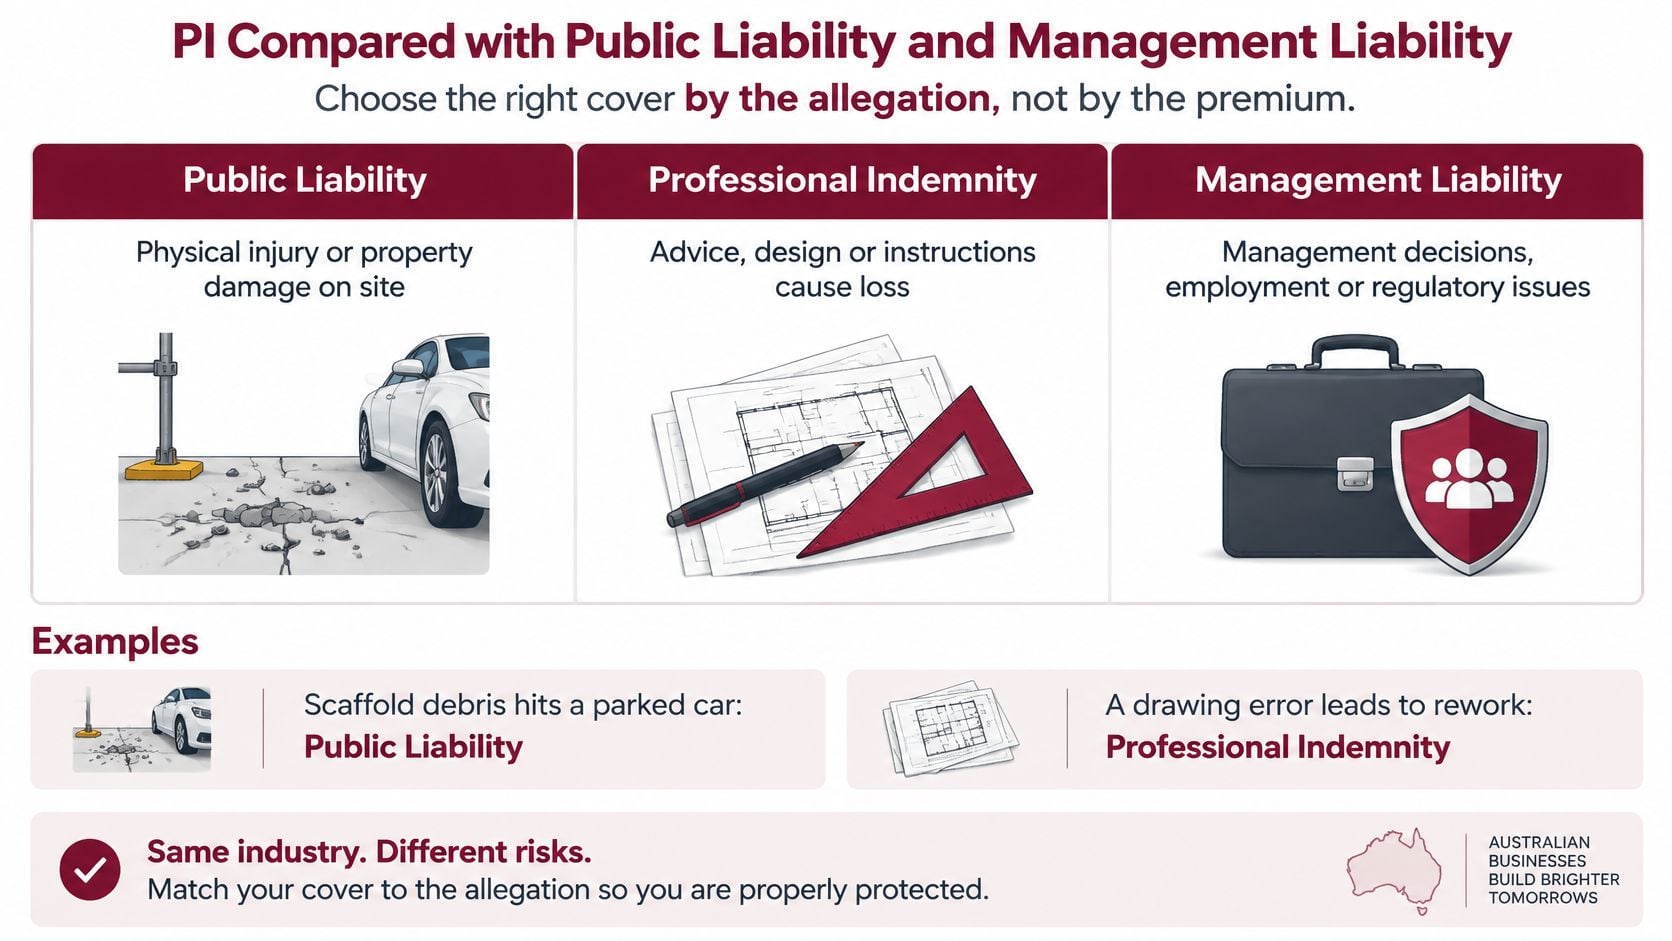
Different allegations on the same site
Scaffold debris falls onto a neighbour's parked car. The neighbour alleges your site operations damaged their property, so public liability is the starting point.
An engineer then discovers that a lintel was undersized. The owner claims redesign, removal, replacement and delay costs arising from negligent calculations, making professional indemnity the policy to examine.
Later, the client accuses a director of knowingly misrepresenting the construction programme. That allegation may require examination under management liability, but a director's involvement alone doesn't establish cover. Professional-services exclusions, dishonesty provisions and the particular management section still matter.
The working distinction is:
- Public liability addresses third-party injury and property damage arising from operations.
- PI addresses covered allegations about professional services, including pure financial loss.
- Management liability addresses specified exposures involving company management, employment and directors' or officers' conduct.
For a closer comparison of the first pair, use this guide to professional indemnity versus public liability when checking your insurance schedule.
Policies outside the comparison
Contract works insurance primarily addresses insured physical loss or damage to construction works during the insured project period. It doesn't replace liability cover for negligent advice.
Statutory residential warranty arrangements, such as NSW Home Building Compensation Fund cover, serve another purpose again. They address specified homeowner protection obligations, rather than operating as professional advice insurance.
Don't assume these policies combine into a shared pool of money for any construction dispute. Each insurer assesses its own trigger, insured parties, exclusions and available limit.
Also check whether a PI contract requirement expects defence costs to be included within the stated limit or paid separately. A certificate showing the requested limit doesn't settle that wording question.
Who Needs PI on a Building Job
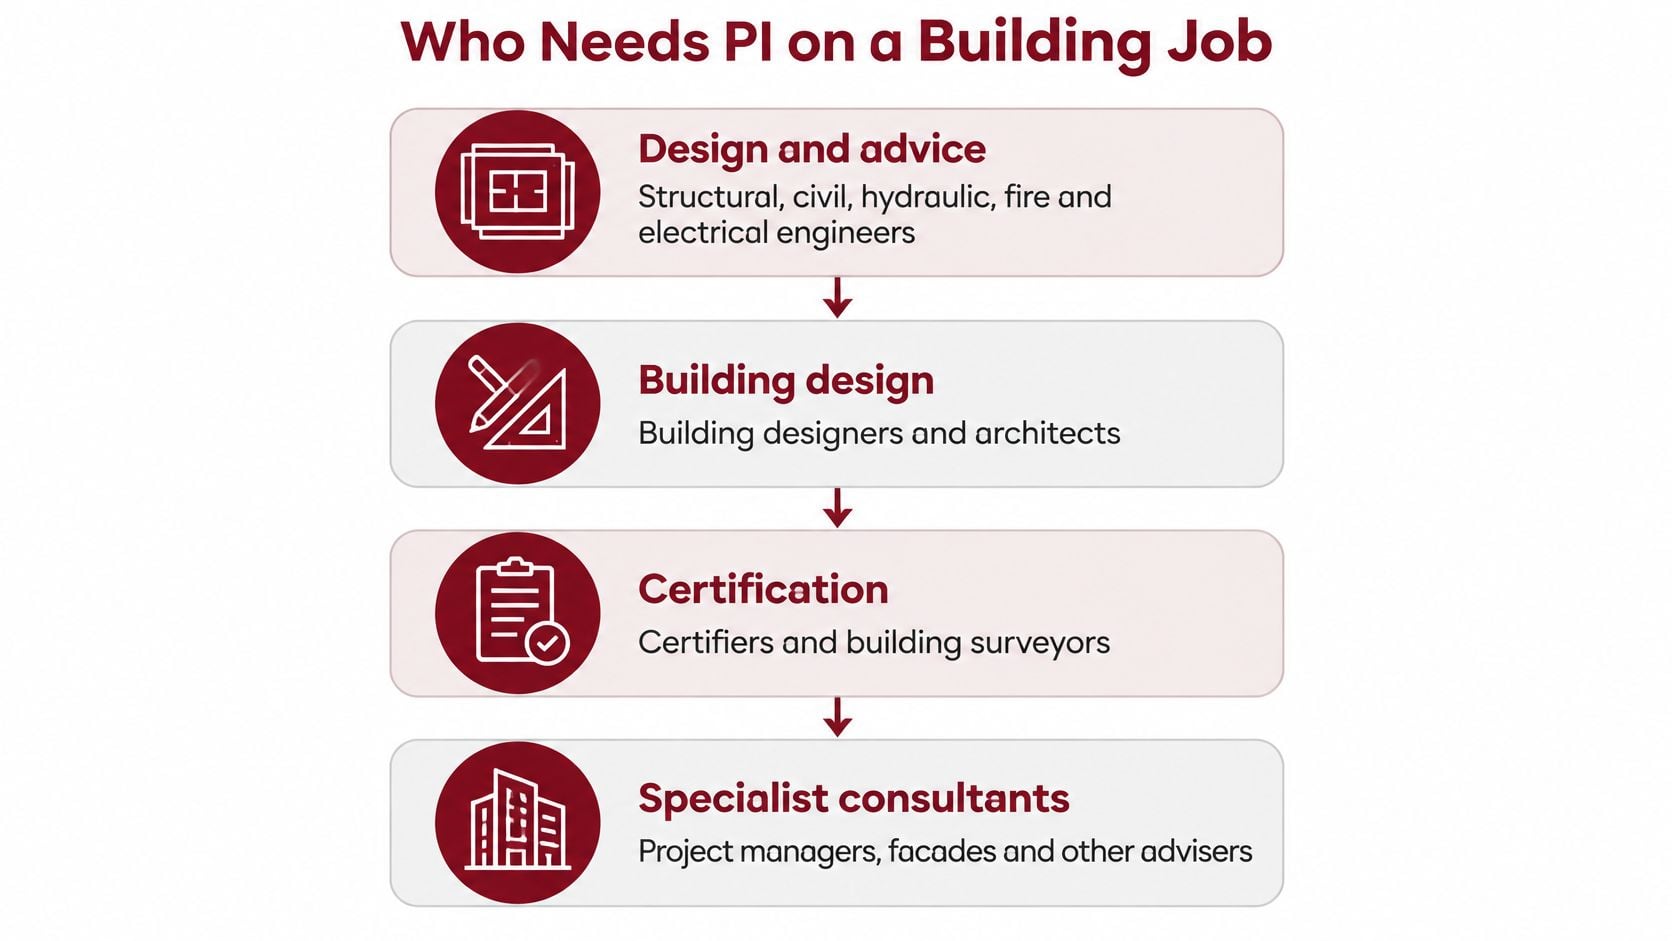
Sort the building chain by the service supplied, not the job title. The table is an exposure guide, not a statement that every listed role has the same statutory insurance obligation.
| Role | Usually needs PI? | Reason |
|---|---|---|
| Structural, civil, hydraulic, fire or electrical engineer | Yes | Design calculations and specifications are advice a client relies on |
| Building designer or architect | Yes | Design output and documentation |
| Certifier or building surveyor | Yes | Certification and inspection opinions |
| Quantity surveyor or estimator | Yes, if a principal relies on the advice | Estimates and cost advice |
| Project manager | Usually yes | Coordinates design and advice on the principal's behalf |
| Energy or access consultant | Yes | Technical compliance advice |
| Design-and-construct builder | Yes | Takes responsibility for consultants' design work |
| Labour-and-materials head contractor | Usually no, if genuinely construction-only | Builds to others' drawings without accepting professional responsibilities |
| Subcontractor preparing shop drawings or certificates | Yes, assess the technical scope | Produces its own technical output |
| Labour-only trade with no design or certification | Usually no | Public liability is the main liability cover |
| Owner-builder or developer giving professional design direction | Yes, assess the professional role | May act as the coordinating professional |
The professional responsibilities can sit at several levels of the same project.
Builders and subcontractors need separate checks
A labour-and-materials builder may start with construction-only responsibilities, then accept a variation requiring a technical recommendation. Review the actual contract before concluding that PI isn't relevant.
A design-and-construct builder has a different problem. Under novation, a consultant's appointment is transferred to another party, often the builder, and the resulting documents may allocate substantial design responsibility to that builder.
Subcontractors shouldn't assume the head contractor's PI automatically insures them. Ask whether your own shop drawings, performance specifications or compliance statements create an independent professional exposure.
Ownership isn't a professional service
A developer choosing finishes or approving a budget isn't automatically acting as a design consultant. The exposure changes when the developer supplies technical instructions, undertakes professional coordination or accepts responsibility for design adequacy.
For help separating those appointments, HireArchitects' guide to preconstruction team roles and responsibilities provides useful context for mapping who supplies each service.
A principal can require PI under a contract even where your occupation doesn't have a general statutory requirement to hold it.
Check your contract, licence, proposals and website together. If they promise design, advice, inspection or certification, have the scope assessed before pricing the tender. The guide to when construction professionals need professional indemnity insurance can help frame that discussion.
How a Claims-Made PI Policy Responds
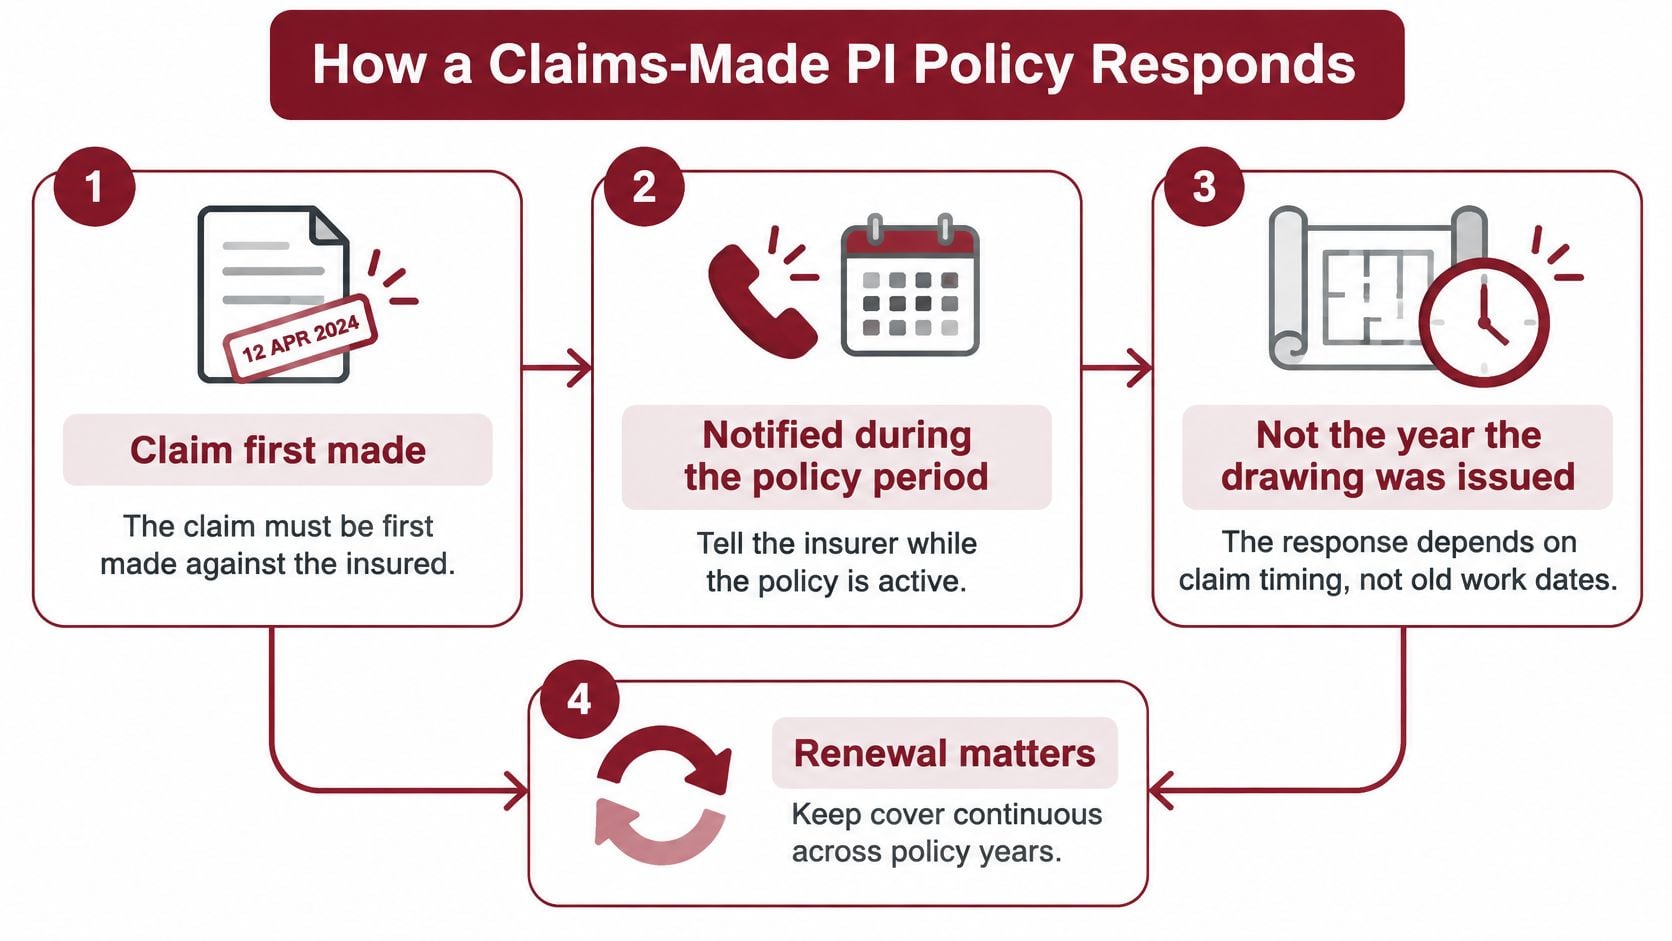
A claims-made and notified PI policy generally responds when a claim is first made against you and notified to the insurer during the applicable policy period. It does not attach to whichever policy you held when you issued the drawing.
APRA's NCPD explanatory notes describe PI as liability cover arising from professional practice, including related legal expenses. The practical trigger is an allegation about professional performance, rather than a fire, flood or damaged item of plant.
The timing relationship is central to the cover.
Start with the claim and notification dates
When a demand arrives, preserve the email, letter or other communication that first set out the allegation. Send it promptly through the insurer's required notification channel, usually with your broker's assistance.
Don't wait for a statement of claim from a court. A demand for rectification costs or an allegation that your advice caused loss may already require action under the wording.
- Record the allegation: Keep the original communication and the date received.
- Preserve the project file: Include the engagement, drawings, revisions, certificates and relevant instructions.
- Seek insurer direction: Don't admit liability, agree a settlement or appoint your own defence team without checking consent requirements.
Check how far back the cover reaches
The retroactive date generally marks the earliest professional acts the policy will consider covering. It's not the deadline for submitting a claim, and it doesn't guarantee that every older job qualifies.
Say the demand concerns a completed project. The current policy may respond if the professional act falls within its retroactive cover and the other conditions are met. Moving that date forward at renewal can exclude earlier work even though the new policy has no break in its start date.
Continuous insurance matters, but uninterrupted dates alone aren't enough. A known circumstance, late notification or a change of insurer can create problems unless the applicable wording and notification arrangements address it.
Don't close the insurance file when you close the project file. Completed work can still generate a later allegation.
Match the insured profession to the work
Compare the policy's business description with your contracts, tender submissions, licence and marketing. A description limited to labour-only installation may not accommodate an allegation about design you also supplied.
For a covered claim, the insurer may fund investigation, solicitors, defence, settlement or damages. The excess is your contribution, while a sublimit is a smaller cap applying to a particular category of cover.
Keep a live register of complaints, demands and circumstances that could lead to claims. Notify them promptly in accordance with the policy rather than leaving them for the renewal questionnaire.
Limits and Exclusions That Change the Outcome
A consultant uses the same detail across several developments. If that detail is defective, separate owners may bring related claims, so a limit that looks adequate for an isolated mistake may be inadequate across the portfolio.
Any-one-claim limits and annual aggregates answer different questions. The first caps an individual claim, subject to how related claims are grouped; the second caps the insurer's total payment across the policy period.
| Factor | Why it changes the limit | Practical test |
|---|---|---|
| Size of one error | Rectification and defence on the largest job can exceed profit | Estimate plausible rectification, delay and defence costs on the biggest contract |
| Annual aggregate | A repeated method can produce several claims | Check the aggregate against connected and unrelated project exposures |
| Contract minimum | The clause sets a floor, not a sizing method | Read the insurance clause and schedule together |
| Defence costs | Costs inside the limit reduce what remains for damages | Confirm costs-inclusive cover or costs in addition |
| Design by others | The head contract may make the builder responsible for consultant error | List who signs drawings and who holds their own PI |
| Retroactive date | Earlier work may fall outside cover if the date moves forward | Match the date to historical professional activities |
Size the exposure, not just the certificate
ASIC's report on professional indemnity insurance explains adequacy in the context of Australian financial services licensees serving retail clients. Its risk-based approach is useful here, but those financial-services requirements aren't construction insurance rules.
For a construction business, examine the largest plausible professional error, concurrent projects, consultant interfaces and contractual indemnities. Include the firm's turnover and capacity to fund the excess, without treating revenue as a substitute for exposure analysis.
Ask how the insurer groups claims arising from a common cause. Also check whether the aggregate can be reinstated, and on what terms, rather than assuming it automatically resets after payment.
Exclusions can outweigh the headline limit
Read exclusions and endorsements together. An endorsement changes the standard policy wording, sometimes expanding cover and sometimes restricting it.
Common issues to have explained include:
- Known circumstances: Problems you knew about before inception may be excluded.
- Assumed contractual liability: Promises extending beyond your ordinary legal responsibility may not be insured.
- Fitness-for-purpose warranties: Guaranteeing a result can create broader liability than agreeing to exercise reasonable professional care.
- Uninsured services: Work outside the declared profession may fall outside cover.
- Territorial restrictions: Check where work can be performed and where proceedings can be brought.
- Conduct exclusions: Fraud, dishonesty, fines and penalties require close reading, including any protection for innocent insured parties.
- Specific subject exclusions: Pollution, asbestos, fee refunds and specified consequential losses may be restricted or excluded.
Don't treat that list as a universal exclusion schedule. Ask the broker to identify which restrictions appear in the proposed wording and which can be negotiated.
A high limit won't correct an unsuitable business description, an excluded service or a retroactive date that removes the relevant work.
Claim Stories from Design Advice and Instructions
These are hypothetical illustrations, not reported claims or insurer statistics. Each shows why an allegation needs to be matched to documents before anyone promises cover.
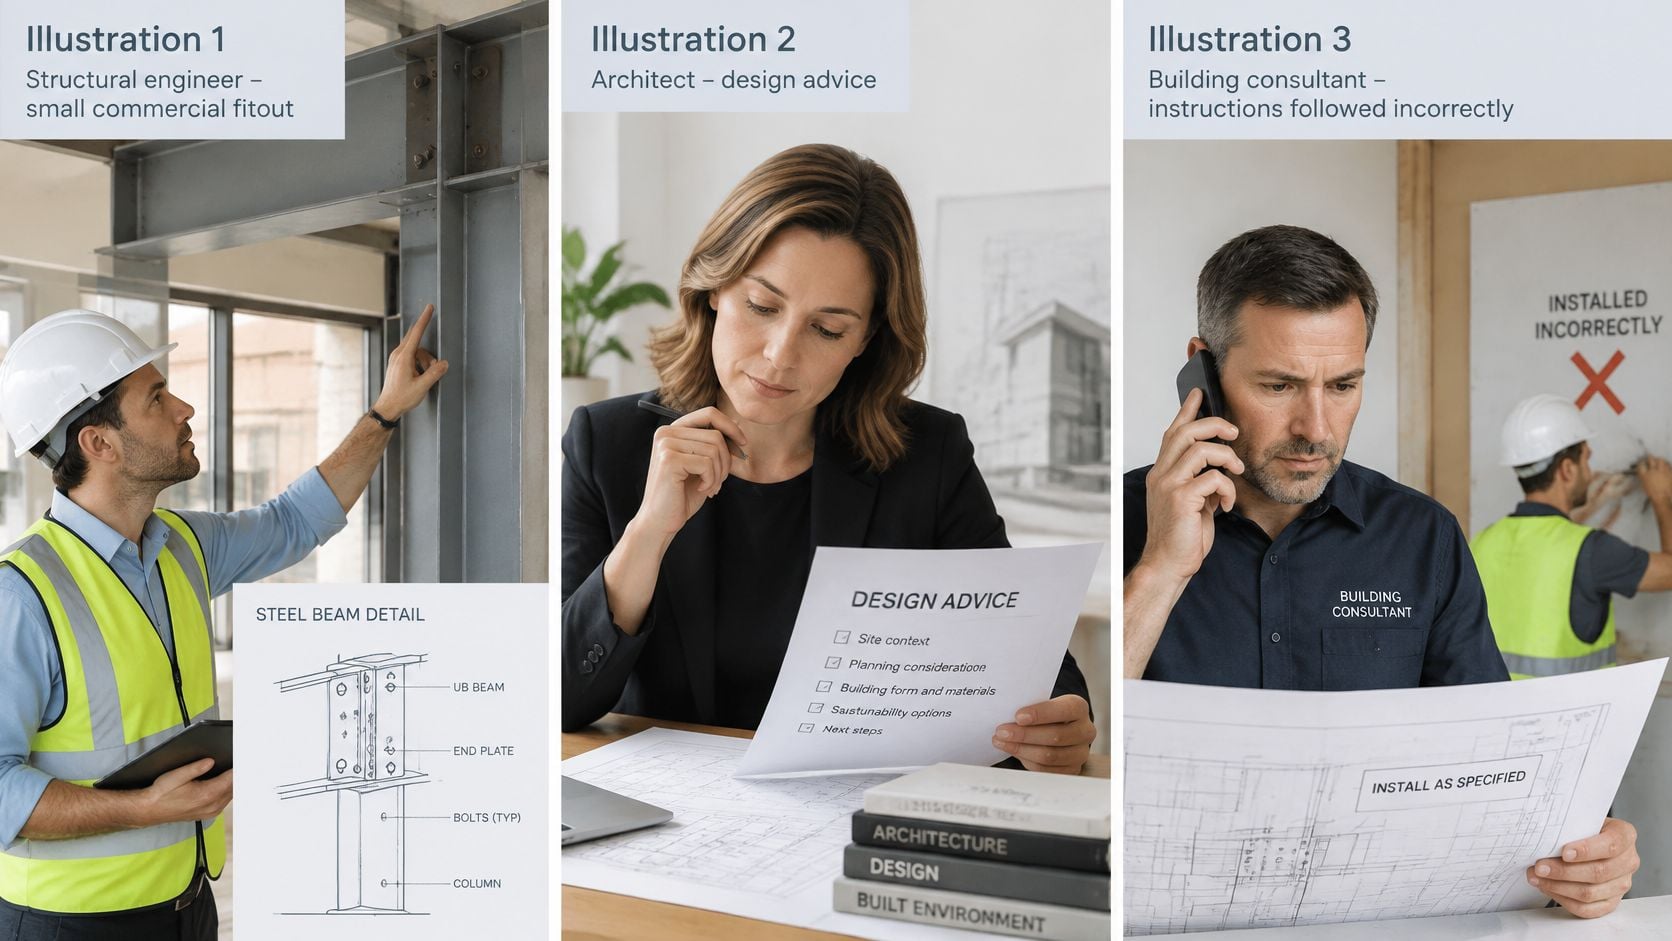
The professional roles may look different, but each supplies something a client relies on.
An undersized beam in a commercial fitout
A structural engineer specifies an undersized steel beam. Before anyone is injured or other property is damaged, the owner demands replacement costs and compensation for delayed opening.
The allegation concerns negligent design, so PI is the relevant starting point rather than public liability for pure financial loss. The engineer gathers the engagement, calculation revisions, policy business description and first demand; the insurer checks notification timing and the applicable excess.
The engagement is particularly important because it establishes which design tasks the engineer accepted. It may also identify instructions or assumptions that affect the defence.
Certification challenged after handover
A building surveyor issues certification, and an owners corporation later alleges that the surveyor missed a waterproofing defect. The surveyor disputes whether the inspection scope required the investigation the owners now say was necessary.
The insurer examines the inspection date against the retroactive date, then checks the first allegation and notification records. The appointment, inspection notes, certificate, insured-services description and excess provisions help determine the response.
The dispute isn't resolved merely because a defect exists. The claimant still needs to establish the professional responsibility and alleged failure relevant to its claim.
For another explanation of the topic, this video provides supplementary context.
A balcony membrane performance specification
A design-and-construct builder issues a membrane performance specification. The membrane subsequently fails, and the owner seeks replacement and associated losses after the construction policy's insured period has ended.
Assume the public liability wording excludes the particular rectification claim. The PI insurer then examines whether the builder's specification was an insured professional service or whether the contract imposed an excluded fitness-for-purpose guarantee.
The deciding documents include the head contract, specification, consultant appointments, policy business description, notification record and excess wording. The absence of injury alone wouldn't justify a public liability declinature.
A labour-only carpenter who followed drawings presents a different exposure from a carpenter who supplied the failed detail. In either case, preserve the instructions: defending an allegation can involve legal expense even when the claimed responsibility is disputed.
Arrange Professional Indemnity Cover Before You Tender
Before committing to a tender's insurance clause, give your broker enough detail to match the policy to the work. A trade label and turnover figure may not capture a business that also provides design or technical advice.
- Split turnover between labour, supply, design and advisory services. Describe technical work included in an overall construction price, even if it is not invoiced separately.
- List your largest current and upcoming contracts. Include their PI requirements, requested retroactive protection and any clauses requiring the principal to be insured.
- Attach your services wording from proposals, your website and relevant licences. Include examples of drawings, certificates or reports you issue.
- Disclose known claims and circumstances, previous insurers and the existing retroactive date. Provide the current schedule and endorsements.
- Ask whether defence costs reduce the policy limit, whether subcontracted design is covered and which contractual promises may need amendment.
Look beyond the cheapest quotation
Consider insurer claims capability alongside premium and policy wording. The Australian Treasury's account of the HIH collapse describes HIH as a major professional indemnity insurer whose collapse in 2001 disrupted access to professional cover.
The premium assessment may depend on your occupation, services, turnover, claims history and requested policy structure. Ask a professional indemnity insurance broker to price the work you sell, rather than relying on a broad trade category.
For projects involving exhibition stand contractors, spell out who is responsible for fabrication, installation, design coordination, structural detailing and certification. Clear responsibilities help the broker understand which professional services the policy needs to cover.
Resolve wording questions before submitting the tender. It is easier to negotiate an insurance obligation before signing than to discover later that suitable cover is unavailable on the required terms.
ABS Insurance Brokers Pty Ltd provides professional indemnity advice and insurance placement for construction businesses and technical professionals, alongside other construction-related covers. Bring your tender clauses, services description and current policy schedule to ABS Insurance Brokers Pty Ltd to discuss limits, historical work and policy wording suited to your responsibilities.