Drone insurance for inspections should reflect both the flight and the service delivered to the client. Photographing a roof, interpreting thermal images and supplying measurements for a construction decision can create different exposures.
This guide helps construction, inspection and surveying businesses prepare a clearer insurance brief. For the underlying aviation cover options, see the ABS drone insurance hub.
Discuss your drone, pilots, work and insurance questions with ABS Insurance Brokers.
Bring your equipment list and operating details so the proposed cover can be reviewed.
Start with the deliverable. Are you supplying unedited images, a progress record, measurements, a defect assessment or professional recommendations? Tell the broker who interprets the information and what the client is entitled to rely on.
A description such as “drone services” does not explain whether the business gives technical advice. Include sample scopes of work and contract terms, especially limitations of liability, accuracy commitments and obligations to repeat work.
Also explain whether your business flies the drone itself or engages a separate operator. Identify which entity signs the client contract and which entity needs to be insured.
If a drone damages a building, aviation liability may be relevant. If an allegedly inaccurate report leads to a client’s financial loss, professional indemnity insurance may require separate consideration. Neither example is a guarantee of cover.
Ask how the proposed policies treat surveying, inspection, measurement, analysis and design-related services. Check for exclusions or conditions that leave a gap between the flight activity and the professional service.
Where professional indemnity is proposed, ask the broker to explain its notification requirements, retroactive date and treatment of known circumstances. Do not wait for a formal legal demand before checking whether an issue needs to be notified.
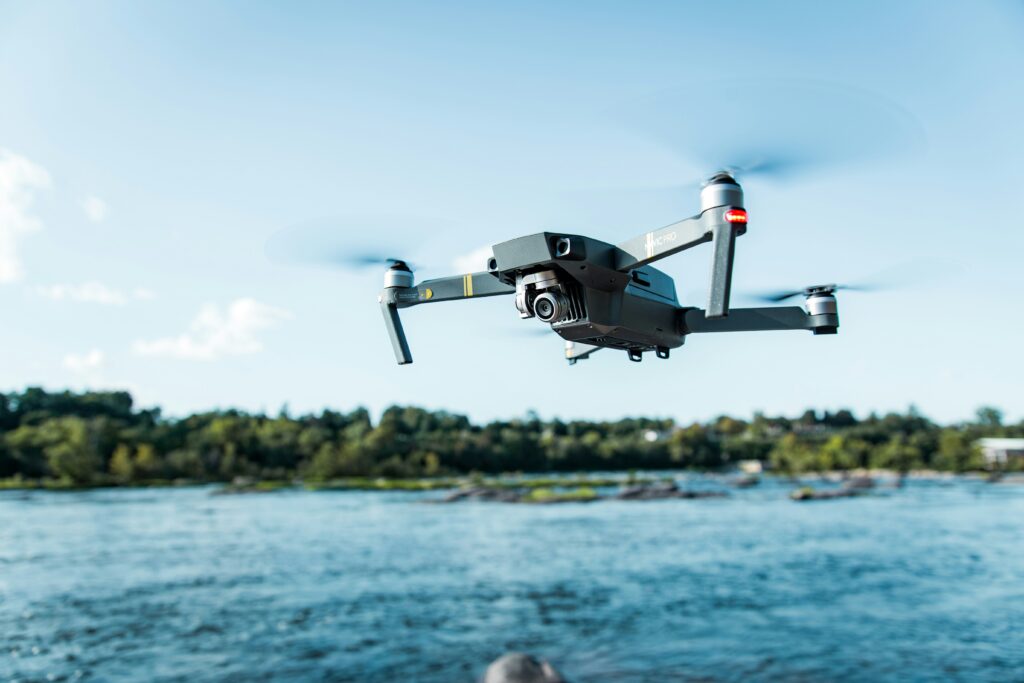
List the aircraft and each significant payload, including thermal cameras or mapping sensors. Record supportable values and clarify hired or borrowed equipment. Ask whether ground equipment and accessories are insured as well as the aircraft.
Explain the sites involved: roofs, industrial facilities, infrastructure corridors and active construction projects may present different operating conditions. Give the insurer the actual flight profile rather than relying on a generic commercial-use description.
Ask about transit, storage, equipment breakdown exclusions, recovery costs and replacement hire separately. An aircraft repair payment does not automatically cover missed site visits, corrupted files or the cost of collecting the data again.
The principal contractor’s insurance should not be assumed to cover your aircraft or your liability. Request the relevant insurance requirements, then check your own construction and business insurance arrangements alongside the aviation policy.
Agree practical responsibilities for access, people on site, take-off and landing areas, communications and changed conditions. A client’s permission to enter the site does not replace aviation requirements.
Consult CASA’s guidance on flying over and near people for the applicable operating restrictions and authorisation pathways. Do not assume workers become part of the drone operation simply because they are on the same project.
Check CASA’s registration requirements for the aircraft used for work. Keep the insurer informed when the service changes, such as moving from photography into measurement or advice.
Do not rely on that assumption. Confirm the contractor’s own cover, the principal’s requirements and any policy provisions concerning aircraft or subcontractors.
The answer depends on your actual service, contract and potential liability. Clearly distinguish image capture from interpretation or advice, and ask the broker to assess the exposure.
Possibly, if both activities are disclosed and accepted under the policy. Confirm this before adding a service, particularly where the client relies on technical conclusions.
Provide an accurate certificate once cover is confirmed, but also check the contract against the policy. A certificate does not expand insured activities or remove exclusions.
Do not assume it does. Ask specifically about rework, data loss, replacement hire and consequential financial loss; each may be treated differently.
Send ABS your inspection or surveying scope, equipment schedule and client insurance clauses. We can help identify the cover questions before you commit to the project.
General information: This article does not take account of your objectives, financial situation or needs. Cover is subject to underwriting, the policy wording, schedule, endorsements, limits, excesses and exclusions. Read the relevant documents and seek advice appropriate to your circumstances. Check current regulatory requirements with the relevant authority.