A surety bond is a three-party guarantee: a surety backs the principal's promise to the obligee, and pays if the principal fails to perform. Unlike insurance, the principal must repay any claim. To get one fast, identify the bond type, apply through a licensed broker, complete underwriting and pay the premium.
If a client, council or head contractor has told you that you need a bond before you can start work, the clock is usually already running. This guide explains what a surety bond is, the main types, what it costs, and the steps that get one issued with the least delay.
What is a surety bond and how does it work?
A surety bond is a written guarantee that a contractor or business will do what it has promised. If it does not, the bond pays the other party, up to an agreed limit. The key point: the bond backs your performance, and you remain responsible for any amount it pays out.
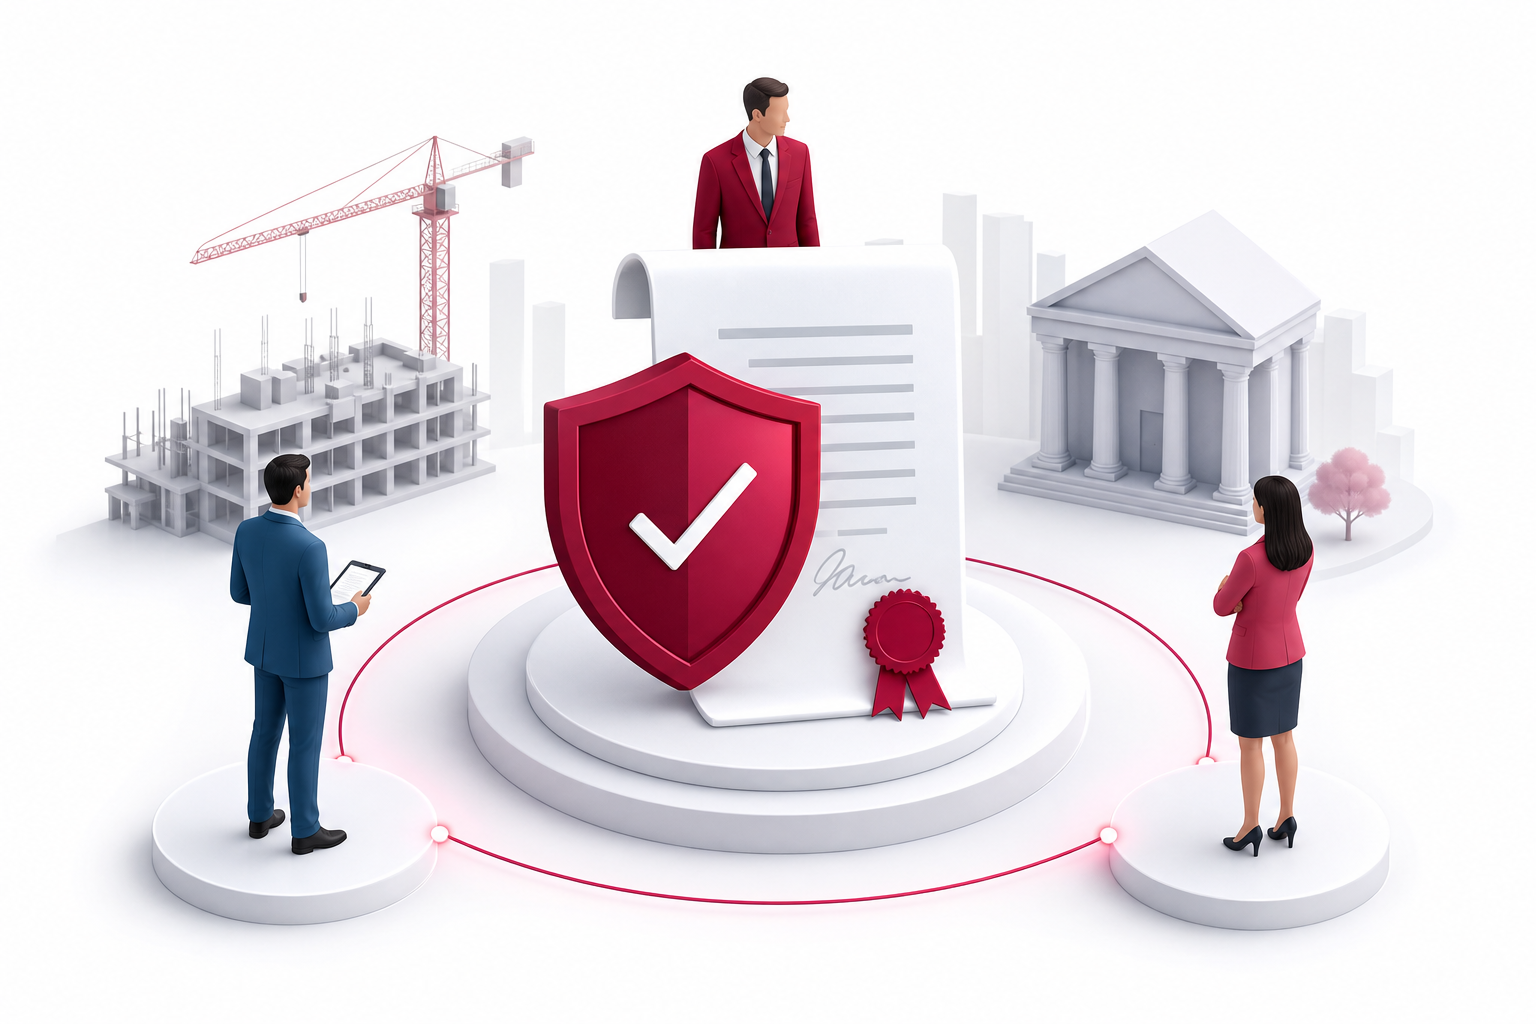
Three parties are involved:
- Principal: the contractor or business that needs the bond and promises to perform.
- Obligee: the party that requires the bond and is protected by it, such as a client, developer or government body.
- Surety: the company that issues the bond and guarantees the principal's performance to the obligee.
Here is a simple example. A builder (the principal) wins a commercial fit-out. The client (the obligee) wants assurance the job will be finished, so the contract calls for a performance bond. A surety reviews the builder's finances and track record, then issues the bond.
If the builder walks away from the job or fails to meet the contract terms, the client can make a claim on the bond. The surety assesses that claim. If it is valid, the surety pays, then looks to the builder to repay it.
The structure explains why sureties look closely at who they bond. They lend their financial backing to your promise. They do not pool risk across many policyholders the way an insurer does.
The sections below cover how a bond differs from insurance, which type fits your situation, what drives the cost, and the practical steps to get one issued.
Is a surety bond insurance? Repayment, indemnitors and the penal sum
Not in the way most people mean it. "Surety bond insurance" is a common search phrase and a common label, but it is misleading. With insurance, you pay a premium and the insurer carries the loss. With a surety bond, the principal must repay the surety for any claim paid out.
The bond protects the obligee. It does not protect you. The premium is the fee for the surety lending its financial backing, not a payment that transfers your risk away.
The role of the indemnitor
Sureties usually require an indemnitor: a person or entity that signs an indemnity agreement promising to reimburse the surety if a claim is paid. For a company, that is often the directors, owners or a related entity. The indemnitor's own assets stand behind the principal's promise, which is why sureties ask for personal and business financial details at application.
The penal sum
The penal sum is the maximum amount the bond can pay. It is the bond's face value, set by the contract or licensing rule that requires it. The surety's exposure to the obligee is capped at that figure, and a claim can never exceed it.
A worked claim example
Say a builder is required to hold a performance bond. The builder defaults partway through the job, and the client proves the loss. The surety pays the client an amount within the penal sum.
The surety then recovers that amount from the builder and, if needed, the indemnitor. The builder has not been "covered". The bond has simply advanced the money to the client, and the builder owes it back.
If you want cover that responds to damage or loss on the job itself, that is a different product. For that, see contract works insurance, and keep the two clearly separated: a bond guarantees performance, while insurance responds to defined losses.
Types of surety bonds: contract vs commercial, with examples
Surety bonds fall into two broad groups: contract bonds and commercial bonds. Which one you need depends on who is asking for it and why.
Contract bonds guarantee performance on a specific project. They are common in construction. Typical examples include:
- Tender (bid) bonds: support a tender by guaranteeing you will enter the contract if you win.
- Performance bonds: guarantee you will complete the work to the contract terms.
- Retention substitutes: a bond given in place of cash retention held back from your progress payments, which keeps your cash flow intact.
Commercial bonds are tied to a licence, permit or statutory obligation rather than one project. They guarantee that a business will follow the rules attached to its licence or registration.
In NSW, a surety bond is usually demanded in one of two ways: by a principal under the contract terms, or by a licensing or regulatory requirement. Check the contract or licence conditions first, because they set the bond type, the penal sum and the exact wording the obligee will accept.
Bond requirements are common in licensing overseas too. Cornerstone Surety Bonds, a vendor, reports that 87% of the US state-level requirements it tracked mandate a bond for licensing. That figure describes the United States, not NSW, but it shows how routine bonds are as a licensing condition. In the US, the Small Business Administration also guarantees bonds for smaller contractors, with contract values totalling $10.6B in fiscal year 2025. No direct equivalent scheme is described here for Australia.
| Bond type | Who usually asks for it | When it is needed |
|---|---|---|
| Tender (bid) bond | Client or head contractor | At tender submission |
| Performance bond | Client or head contractor | At contract signing or before work starts |
| Retention substitute | Head contractor or client | When cash retention would otherwise be withheld |
| Licence or commercial bond | Regulator or licensing body | At licence application or renewal |
If you work on building and construction sites, it also helps to know how bonds sit alongside your other cover. See construction insurance for builders and contractors for the policies that respond to loss, as opposed to guarantees that back your performance.
How much does a surety bond cost?
The cost of a surety bond is the premium, and it is a small percentage of the bond amount (the penal sum). You pay it to the surety for lending its financial backing. This is the same thing people mean when they ask about a "premium surety bond": the fee charged to issue the bond, not a special class of bond.
Several things set the percentage the surety applies:
- Financial strength: your balance sheet, cash flow and working capital.
- Experience: your track record on similar work and with similar project sizes.
- Bond size: the penal sum, relative to what your business can carry.
- Project risk: the type of work, the contract terms and the obligee.
A contractor with strong financials and a clean history is generally priced more favourably than one with thin accounts or limited experience. The same contractor can also be quoted differently for two different bonds.
That is why no honest figure can be given without a quote. The surety needs your financial details and the bond wording before it can price the risk. Ask for the premium, any fees and the bond's term in writing before you commit.
Who pays for a surety bond?
The principal pays. The contractor or business that needs the bond covers the premium, not the obligee who benefits from it. The obligee simply receives the guarantee.
In practice, many contractors allow for the cost when they price a tender, so it is recovered through the contract rate rather than absorbed as an overhead. Check whether your contract allows the bond cost to be claimed as a separate item or expects it to sit within your price.
Because the principal also carries the repayment obligation if a claim is paid, the premium is only part of the commitment. The indemnity agreement matters as much as the invoice.
How to get a surety bond fast: step by step
You can get a bond issued quickly if you prepare before you apply. Speed depends mostly on how complete your information is and how clear the bond requirement is. Industry benchmarking from Tinubu shows that only 12% of organisations successfully provide same-day turnaround for small commercial bonds. Treat same-day issuance as the exception and plan for underwriting time. This is a general industry benchmark, not an Australian statistic and not a promise about any one broker.
- Identify the bond type you need. Read the contract or licence conditions to find the bond type, the penal sum and the wording the obligee will accept. Get this wrong and you will lose time reissuing.
- Find a licensed broker. A licensed insurance agent or producer acts as the liaison between you and the surety company. This is also the answer to where to get a surety bond: you generally go through a broker, who places it with a surety.
- Complete the application. Provide basic business, personal and project-specific information. Have your financial statements, project details and contract documents ready.
- Wait for underwriting. The surety reviews the risk and decides whether to approve the bond. Questions from the underwriter are normal, and quick answers keep the file moving.
- Pay the premium. Once approved, you pay the premium and the bond is issued to the obligee.
ABS Insurance Brokers is an Australian-owned insurance brokerage that sources and arranges specialist insurance policies for builders, construction businesses, and general commercial clients. You can contact the team by phone or through the online quote request form, and a broker works with you to identify the right cover. ABS operates as part of the Steadfast Network, which gives it access to a wide range of insurers and products.
Pricing is not publicly available, so ask for a quote once you know the bond type and penal sum.
What slows a surety bond down, and a checklist to avoid it
Delays almost always come from the file, not the surety. An underwriter cannot approve what they cannot assess, and each missing document restarts the clock. Because only 12% of organisations manage same-day turnaround on small commercial bonds, most bonds take longer. The goal is to remove avoidable waiting.
The usual causes are:
- Incomplete financials: missing or out-of-date statements, or accounts that do not match what you stated.
- Unclear bond wording: an obligee's form that has not been supplied or agreed, so the penal sum and conditions are uncertain.
- Uncertain project details: no contract value, scope or timeline for the surety to assess.
- Slow answers: underwriter questions left sitting for days.
Before you apply, have these ready:
- Recent financial statements for the business
- Personal and business financial details for any indemnitor
- A copy of the contract or licence condition requiring the bond
- The obligee's required bond wording and the penal sum
- Project scope, value and timeline
FAQs
What is the difference between a surety bond and a letter of credit?
A surety bond is a guarantee from a surety, and you repay the surety if it pays a claim. A letter of credit is a bank's undertaking to pay, usually backed by cash or security held against your facility. A bond generally keeps your cash and borrowing capacity free. A letter of credit commonly ties them up.
What is an investment bond in Australia, and is it the same as a surety bond?
No. An investment bond is a savings and investment product, usually a life insurance-based policy, held for growth over time. A surety bond is a performance guarantee issued to an obligee. They share the word "bond" but serve entirely different purposes and are not interchangeable.
Is it worth buying Australian government bonds instead of a surety bond?
No. Government bonds are debt securities you buy as an investment. They do not guarantee your performance to a client, and no obligee will accept them in place of a required surety bond. If a contract or licence calls for a bond, you need a surety bond issued by a surety.
What is a premium surety bond?
The term refers to the premium: the fee you pay the surety to issue the bond. It is not a special class of bond. The premium is a small percentage of the penal sum, set by your financial strength, experience, bond size and project risk. A quote gives the precise figure.
Can I get a surety bond with poor credit or limited financials?
It is harder, but not always impossible. Sureties assess financial strength, experience and the size of the bond against what your business can carry. Weaker financials may mean a smaller bond, extra security or an indemnitor with stronger assets. A broker can tell you what a surety is likely to accept before you apply.
Is a surety bond the same as surety bond insurance?
No. "Surety bond insurance" is a common label, but it is misleading. A bond protects the obligee, and the principal must repay any claim the surety pays. Insurance transfers the loss to the insurer. If you need cover for loss or damage on the job, see insurance for contractors.
Conclusion
A surety bond is a guarantee of your performance, not insurance. The obligee is protected, you pay the premium, and you repay any claim. The route to one is short: confirm the bond type, go through a licensed broker, complete underwriting and pay.
Start by reading the contract or licence condition to confirm the bond type, penal sum and wording. Then gather your financials and project details before you apply, so underwriting is not waiting on you.