Insurance Broker vs Direct Insurance: A Side-by-Side View
Insurance broker vs direct insurance: which approach suits your needs? A broker can compare options from the insurers they access and help with advice and claims. Buying direct lets you deal with the insurer yourself. Compare the scope of service, policy terms and total cost before deciding.
Both channels have real merit. A builder arranging contract works cover faces a very different set of needs than someone renewing a home contents policy online. Rather than a blanket verdict, this article gives you a practical framework to match your situation to the right channel.
Insurance Broker vs Direct Insurance: How the Two Channels Compare
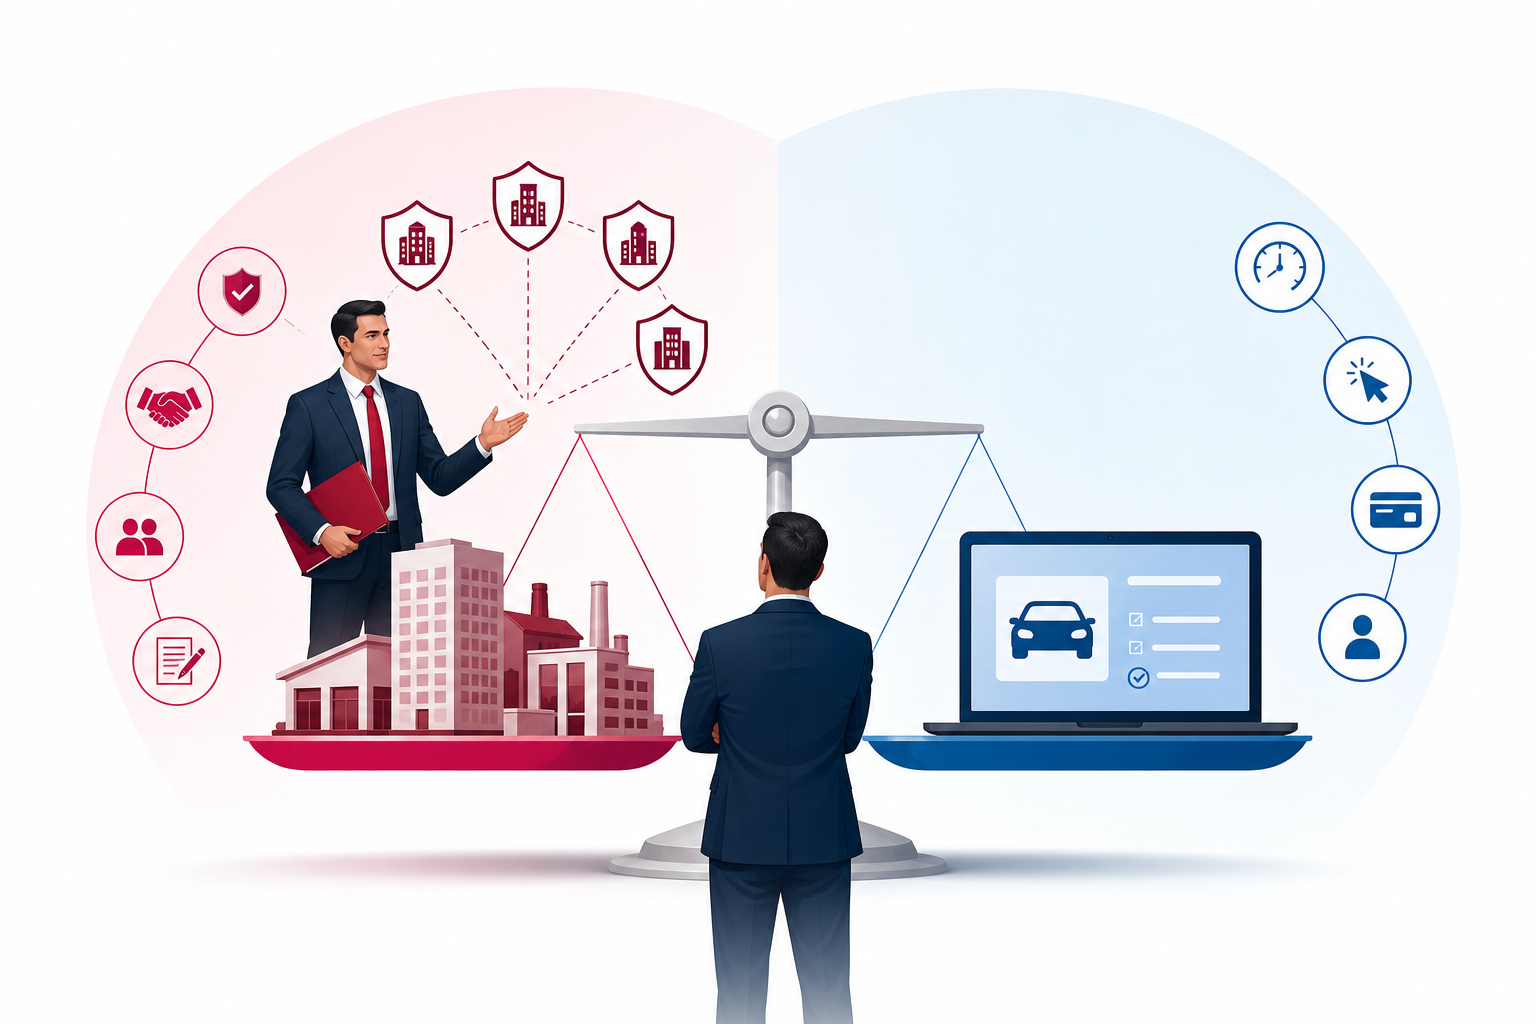
The two channels differ most sharply on who they represent and how much product choice they offer. A broker represents you; a direct insurer represents itself.
Independent agencies and brokers handle 87.2% of commercial insurance placed globally, which reflects how well the broker model fits complex risks. The table below maps both channels across the dimensions that matter most to buyers.
| Channel | Who it represents | Product access | Claims support | Best suited for |
|---|---|---|---|---|
| Insurance Broker | The buyer | Multiple carriers | Independent advocate negotiates on your behalf | Complex, commercial, or specialist risks |
| Direct Insurance | The insurer | Single company's products only | You manage the process yourself | Standard personal cover with straightforward needs |
Brokers owe a fiduciary duty of care to the client, not the insurer. Direct insurers sell proprietary products through websites, apps, or call centres, and you navigate renewals and claims without an independent intermediary.
What Does an Insurance Broker Actually Do?
A broker acts as a licensed intermediary who represents you, not the insurer, when placing your cover. That distinction shapes every part of the relationship.
When you engage a broker, they assess your risk profile, approach multiple carriers, and negotiate terms on your behalf. Initial quotes typically take one to two business days. Because brokers owe a fiduciary duty of care to the client rather than to any insurer, their advice is structurally aligned with your interests, not with a carrier's sales targets.
The claims stage is where that alignment shows most clearly. A broker advocates for you during settlement, which matters when a claim is disputed or the policy wording is ambiguous. For businesses with exposures such as construction liability, professional indemnity, or specialised plant and equipment, that advocacy can affect the final payout.
According to independent market data, independent agencies captured 87.2% of commercial insurance lines in 2024. That figure comes from the US market, but it reflects a consistent global pattern: the more complex the risk, the more buyers rely on brokers.
How Does Direct Insurance Work?
Direct insurers sell policies straight to consumers through their own websites, apps, or phone lines, with no intermediary involved. The process is quick: you enter your details, receive a price, and buy cover in minutes.
The trade-off is product breadth. A direct insurer can only offer policies from its own range. If those products do not match your risk profile closely, nobody in the transaction will flag that gap. You also manage renewals yourself and handle any claims without independent support.
Direct insurers invest heavily in marketing to reach consumers at scale, spending $1.6 billion on advertising in the US alone. That spend supports brand recognition and digital convenience, which suits buyers with straightforward risks. A standard home contents policy or a basic car insurance renewal are good examples of where the direct channel works well.
Direct insurance becomes less suitable when your needs sit outside a standard product template. A sole trader with public liability exposure, or a builder needing contract works cover, will often find that direct products either do not exist or carry exclusions that a broker would have flagged.
Is Insurance More Expensive If You Use a Broker?
Using a broker does not automatically cost more, and in many cases it costs less. Brokers generally have access to over 30 carriers and can produce meaningful premium savings of $500 or more per year by bundling policies and putting carriers in competition, according to smartinsurance101.com's 2026 analysis. That finding is not a guaranteed outcome, but it illustrates the potential effect of carrier competition.
Brokers earn income through commissions paid by the insurer on placed policies, or through a fee charged to the client, or a combination of both. In Australia, brokers are required to disclose their remuneration, so you can see exactly what they earn on your policy.
Direct insurers price their policies to cover their own distribution and marketing costs. Those costs are embedded in the premium rather than disclosed separately. Neither channel is inherently cheaper: the clearest comparison is to get quotes from both using identical coverage specifications, then weigh the total cost against the coverage terms.
To run that comparison yourself, gather quotes from direct insurers through their websites, then submit the same requirements to an independent broker. Compare the final premiums with deductibles and exclusions held constant.
Which Option Is Better for Australian Businesses?
For most Australian businesses, the broker channel offers a better fit than buying direct. Commercial risks such as public liability, professional indemnity, contract works, and management liability are rarely served well by off-the-shelf direct products.
The broker model is well established in the Australian commercial market. The Steadfast Network, to which many Australian brokers belong, gives member firms access to a broad panel of insurers and products that individual buyers cannot reach on their own.
ABS Insurance Brokers is an Australian-owned insurance brokerage that sources and arranges specialist insurance policies for builders, construction businesses, and general commercial clients. The firm operates as part of the Steadfast Network, which extends its access to a wide range of carriers and policy structures. Clients contact the team by phone or via an online quote request form, and a broker works with them to identify the right cover.
Other Australian brokers serving commercial clients include Findex, which provides general insurance brokerage through an alliance with Findura Insurance and Risk Solutions and operates within the Community Broker Network. Per aubiz.net and findex.com.au, Findex covers life, income protection, and commercial risk. Allcover focuses on tailored business packages for Brisbane-based clients, including liability, commercial property, and cyber cover, with annual renewal reviews to check that coverage levels remain appropriate, per allcover.au.
For Australian business owners with anything beyond simple personal cover, broker access to specialist carriers and independent claims advocacy are the two factors most worth weighing against the convenience of buying direct.
How Do You Choose Between a Broker and Direct Insurance?
The decision comes down to risk complexity, business versus personal needs, and how much claims support matters to you. Use the checklist below to map your situation to the right channel.
Choose a broker if:
- You run a business, trade, or construction operation with liability exposure.
- Your risk involves multiple policies that could be bundled or coordinated.
- You have had a claim disputed or expect claims to be complex.
- You need cover that is not available as a standard direct product.
- You want independent advice on policy wording, exclusions, and limits.
Choose direct insurance if:
- You need standard personal cover such as home contents or a straightforward car policy.
- Speed and simplicity matter more than breadth of carrier choice.
- Your risk is low-complexity and the direct product matches your needs exactly.
For guidance on evaluating individual brokers once you have decided to use one, the article on how to choose an insurance broker covers the key questions to ask and the credentials to look for.
Brokers with access to over 30 carriers can produce meaningful premium savings through competition alone, according to smartinsurance101.com's 2026 data. That advantage is most pronounced when your risk profile does not fit neatly into a single insurer's standard product.
FAQs
What is the downside of using an insurance broker?
The main downsides are time and process. Getting broker quotes typically takes one to two business days rather than minutes. Some brokers earn commission from insurers, which creates a potential conflict of interest, though Australian law requires full remuneration disclosure. For very simple personal policies, working through an intermediary may not be worth it when a direct product fits your needs exactly.
Do insurance brokers get paid a commission by the insurer?
Yes, in most cases. Brokers typically earn a commission from the insurer on each policy placed, a fee charged directly to the client, or a combination of both. In Australia, brokers must disclose their remuneration under the Corporations Act. Knowing what your broker earns lets you assess whether their recommendation is influenced by commission rates across different carriers.
Can a broker get me cover that I cannot buy direct?
Yes. Brokers access a panel of multiple carriers, including specialist underwriters whose products are not available to the public. For risks such as contract works, professional indemnity for niche trades, or high-value commercial property, the broker channel often provides policy options that simply do not exist in the direct market.
Is direct insurance faster to set up than going through a broker?
For standard personal cover, yes. Direct insurers let you buy online in minutes. A broker typically needs one to two business days to gather and present quotes. That speed difference matters less for complex commercial risks, where getting the policy terms right is more important than getting cover in place quickly.
What happens if my broker gives me bad advice?
Licensed insurance brokers in Australia operate under the Corporations Act and must hold an Australian Financial Services licence. If a broker gives advice that leads to a financial loss, you can lodge a complaint with the Australian Financial Complaints Authority (AFCA). Brokers must also carry professional indemnity insurance, which provides a route to compensation if negligent advice causes you harm.
Conclusion
An insurance broker represents your interests across multiple carriers, handles negotiation, and supports you through claims. Direct insurance offers speed and simplicity for standard personal policies. Neither channel is universally better: the right choice depends on how complex your risk is and how much independent support you need if something goes wrong.
If you run a business, work in construction, or carry any liability exposure, start by speaking with a broker and comparing their quotes against what is available direct, using identical coverage terms. For personal cover with a straightforward risk profile, the direct channel is a reasonable starting point. Either way, comparing both channels on the same policy specifications before you commit is the single most useful step you can take.