You're checking the weather for a weekend flight when a client asks whether you can stop at a regional project site on the way. A friend might fly the return leg, and the aircraft will stay outside overnight instead of returning to its hangar. Before checking the fuel, check whether your private aircraft insurance describes that flight.
The premium matters, but the wording determines how the insurer assesses a claim. Your declared use, permitted pilots and operating locations deserve as much attention as the aircraft's insured value.
Table of Contents
- What Private Aircraft Insurance Covers at a Glance
- What Drives Your Premium and Policy Terms
- How Your Flying Purpose Changes Your Cover
- Common Exclusions That Leave Owners Exposed
- Protecting Your Aircraft Against Weather and Location Risk
- How to Arrange Private Aircraft Cover in Australia
- Arrange Your Cover Review at Bankstown Aerodrome
What Private Aircraft Insurance Covers at a Glance
Private aircraft insurance is a set of covers, each responding to a different loss, rather than one blanket promise to pay. You can insure the aircraft itself, your legal liability, passenger exposures and certain recovery expenses, but each part has its own conditions.
A hull policy doesn't automatically protect you when flying someone else's aircraft. Nor does insuring your aircraft mean you're covered for damage to another owner's aircraft entrusted to your care.
Private aircraft cover parts and what to check
| Cover part | What it pays for | What to check |
|---|---|---|
| Hull (all risks) | Damage to or loss of the insured aircraft | Excess, agreed or market value, and wear and tear exclusions |
| Legal liability | Third-party injury and property damage for which you're legally liable | Liability limit and which flights are covered |
| Passenger liability | Covered liability for injury to people carried on board | Limit per passenger and per occurrence |
| Non-ownership liability | Covered claims arising when flying an aircraft you don't own | Whether aircraft you have regular access to are excluded |
| Hangarkeepers liability | Covered damage to other people's aircraft in your care | Applies only if you store or service aircraft for others, within the insured activities |
| Recovery and salvage | Covered costs of removing a wrecked aircraft from a site | Sub-limit amount and whether remote recovery is included |
All risks doesn't mean every cause of loss is insured. Read that description alongside the exclusions, insured operations and conditions. Also distinguish between ground-only protection and cover that includes flight, rather than assuming every hull quotation offers the same scope.
Australia's fleet illustrates why a single standard package won't suit every owner: BITRE's Australian Aircraft Activity 2024 report recorded 15,051 aircraft on the VH register at 31 December 2024, up 1.3%, and approximately 1.376 million hours flown by VH-registered general aviation aircraft during 2024. Pleasure flying, instruction, business travel and aerial work call for different declarations.
For an owner who only flies their own aircraft recreationally, some specialist extensions may be unnecessary. For an owner who borrows aircraft or stores aircraft for others, a hull-and-liability package alone may leave a separate exposure unresolved.
Before signing, confirm:
- Hull value: The amount insured and the settlement basis.
- Liability limit: The total available for a covered occurrence.
- Passenger cover: Who's included and any passenger-specific restrictions.
- Sub-limits: Smaller caps applying to particular expenses or losses.
What Drives Your Premium and Policy Terms
Premium factors and what to declare
| Factor | Why insurers care | What to declare |
|---|---|---|
| Aircraft type and value | Sets replacement and repair cost | Make, model, year, avionics and proposed agreed or market value |
| Pilot licence and experience | Helps assess ability to handle the aircraft | Licence, total hours, type ratings and recent flying |
| Annual flying hours | Indicates time exposed to flying-related risks | Expected annual hours and their split by activity |
| Operating base | Identifies hangar, runway and weather exposure | Home airport and overnight storage arrangements |
| Purpose of flying | Pleasure, business, training and aerial work involve different operations | Every intended purpose |
| Passengers | Helps assess passenger and third-party liability exposure | Typical number, age and type of passengers |
| Claims history | Allows assessment of previous losses and circumstances | Prior claims, losses and declined or cancelled cover |
| Pilot list | Establishes who may fly under the policy | Every proposed pilot, their role and any hired pilots |
The insurer prices more than the asset. The proposal needs to describe the aircraft as it's operated, not its registration and purchase price.
Avoid presenting estimates as certainty. If annual hours are provisional, say so and explain the intended split between activities. If a pilot's recency or a storage arrangement is changing, identify the change rather than submitting last year's information unchanged.
Accident frequency isn't the whole price
CASA's 2024–25 annual report recorded 168 aviation accidents across all sectors, against a 10-year average of 198.1, including 55 in non-commercial aviation, approximately 32.7% of the total. Those counts provide safety context, not a personal premium calculator.
Insurers also consider severity, meaning the potential cost of a loss. A repairable aircraft incident can involve passenger injury, damage to property, recovery expenses and legal defence, not just the engineering invoice. Conversely, national accident counts don't establish the likelihood of a claim for a particular owner, aircraft or mission.
Comparison rule: A lower premium paired with a higher excess or smaller liability limit isn't a like-for-like saving.
Compare the excess, liability limit and hull valuation basis before comparing price. An agreed-value arrangement establishes an insured amount subject to the settlement wording; market-value wording requires attention to how the aircraft's value will be established at loss.
A higher excess can be a deliberate choice if you can comfortably fund it. Reducing liability protection to match a cheaper quote deserves more caution, because your aircraft's value doesn't cap the harm an accident could cause to others.
How Your Flying Purpose Changes Your Cover
Flying activities and their effect on cover
| Activity | Example | What to disclose | Likely policy effect |
|---|---|---|---|
| Pleasure flying | Weekend flights with family | Purpose as pleasure | Standard private cover, subject to wording |
| Occasional business travel | Flying to client meetings | Each business trip type | May need a broader use rating |
| Cost-sharing | Friends contribute to fuel | Any contributions received | Can change how the flight is classed |
| Repositioning flight | Moving the aircraft to a new base | Route and date | Usually needs notice and may need specific cover |
| Employee or hired pilot | Pilot paid to fly the aircraft | Name, licence and role | Pilot must meet the listed criteria and any naming requirement |
| Property or construction use | Surveying a building site | Purpose of each flight | Can fall outside a private rating |
| Training | Instructor flying a student | Instruction activity | Usually rated separately |
These are disclosure prompts, not automatic coverage decisions. The insurer's definitions and endorsements control the answer, and insurance classification doesn't replace compliance with aviation operating requirements.
BITRE's Economic Measures of General Aviation in Australia recorded 9,526 aircraft used in general aviation excluding charter in 2022, with 51% used at least partly for joy or recreational flying. The important distinction is “at least partly”: recreational flying and other uses can involve the same aircraft.
Describe the mission, not just the ownership
A privately owned aircraft isn't necessarily used solely for private pleasure. Flying yourself to a client meeting is different from conducting an airborne inspection of a building site, even when neither flight involves selling tickets.
Say a family holiday includes a friend who contributes towards fuel. Declare the contribution arrangement rather than assuming the social purpose settles the insurance classification.
Likewise, a client travelling with you to a project meeting introduces facts that “business travel” alone may not explain. State who's aboard, why they're travelling and whether anyone pays for carriage.
An owner-flown aircraft also needs a different description from one flown by an employee, contractor or hired pilot. When the arrangement involves an aircraft you don't own, consider the separate issues explained in non-owned aircraft liability for pilots and businesses.
Before the next flight:
- Report purpose changes: Explain the actual task, including payments or contributions.
- Update people: Identify new passenger categories and proposed pilots.
- Revise activity estimates: Notify changes in frequency and obtain written confirmation of any required endorsement.
Don't treat a submitted notification as acceptance. Where the operation needs approval, obtain that approval before undertaking it.
Common Exclusions That Leave Owners Exposed
A licensed pilot isn't automatically an insured pilot. The policy may require a named individual, specified experience, particular ratings or other conditions. Permission from the aircraft owner doesn't override those requirements.
The same distinction applies to permitted use. An aircraft can be legally operated yet used outside the activities described in its insurance contract.
Exclusions to test against your flying
- Pilot restrictions: A friend takes the controls but isn't named and doesn't satisfy the applicable pilot clause.
- Use and territory restrictions: The aircraft undertakes paid carriage or a flight outside the insured operating area.
- Passenger conditions: The operation carries more passengers, or a different passenger category, than the policy allows.
- Airworthiness and maintenance: An overdue requirement or known defect raises an issue under the policy's conditions.
- Wear and deterioration: An owner presents progressive corrosion or worn components as accidental hull damage.
- War and hostile acts: The cause of damage falls within an exclusion or requires separate protection.
The application of an exclusion depends on its wording, the circumstances and applicable law. Don't assume every breach automatically defeats every claim, but don't rely on that qualification as a substitute for arranging the right cover.
Consider an owner who lets a friend fly a trip charged to passengers. If the friend falls outside the pilot clause and the flight falls outside the permitted use, the insurer may decline the claim, subject to the contract and applicable law.
Test the policy against a flight you genuinely intend to make, not an idealised flight that avoids every difficult detail.
Get the answer in writing
Read the schedule, endorsements and full wording together. Ask for an explanation of how the insurer would assess your proposed flight, including its pilots, passengers, purpose and route.
Keep the supporting records too. Pilot qualifications, maintenance documents and evidence of the declared operation can matter when making an aviation insurance claim after an aircraft incident.
Before acceptance, resolve these questions:
- Who may fly it? Identify the applicable naming and qualification requirements.
- What use is covered? Match the definition to your real activities.
- What won't it pay for? Identify exclusions and conditions that could affect those activities.
Protecting Your Aircraft Against Weather and Location Risk
A storm crosses a regional grass strip overnight. Your aircraft remains tied down and appears undamaged, but floodwater blocks access and debris covers the runway. You need to establish airworthiness, arrange access and decide whether the aircraft can safely move.
That's a different insurance problem from a straightforward hail-damage claim. An intact aircraft can still be inaccessible or require inspection before flight.
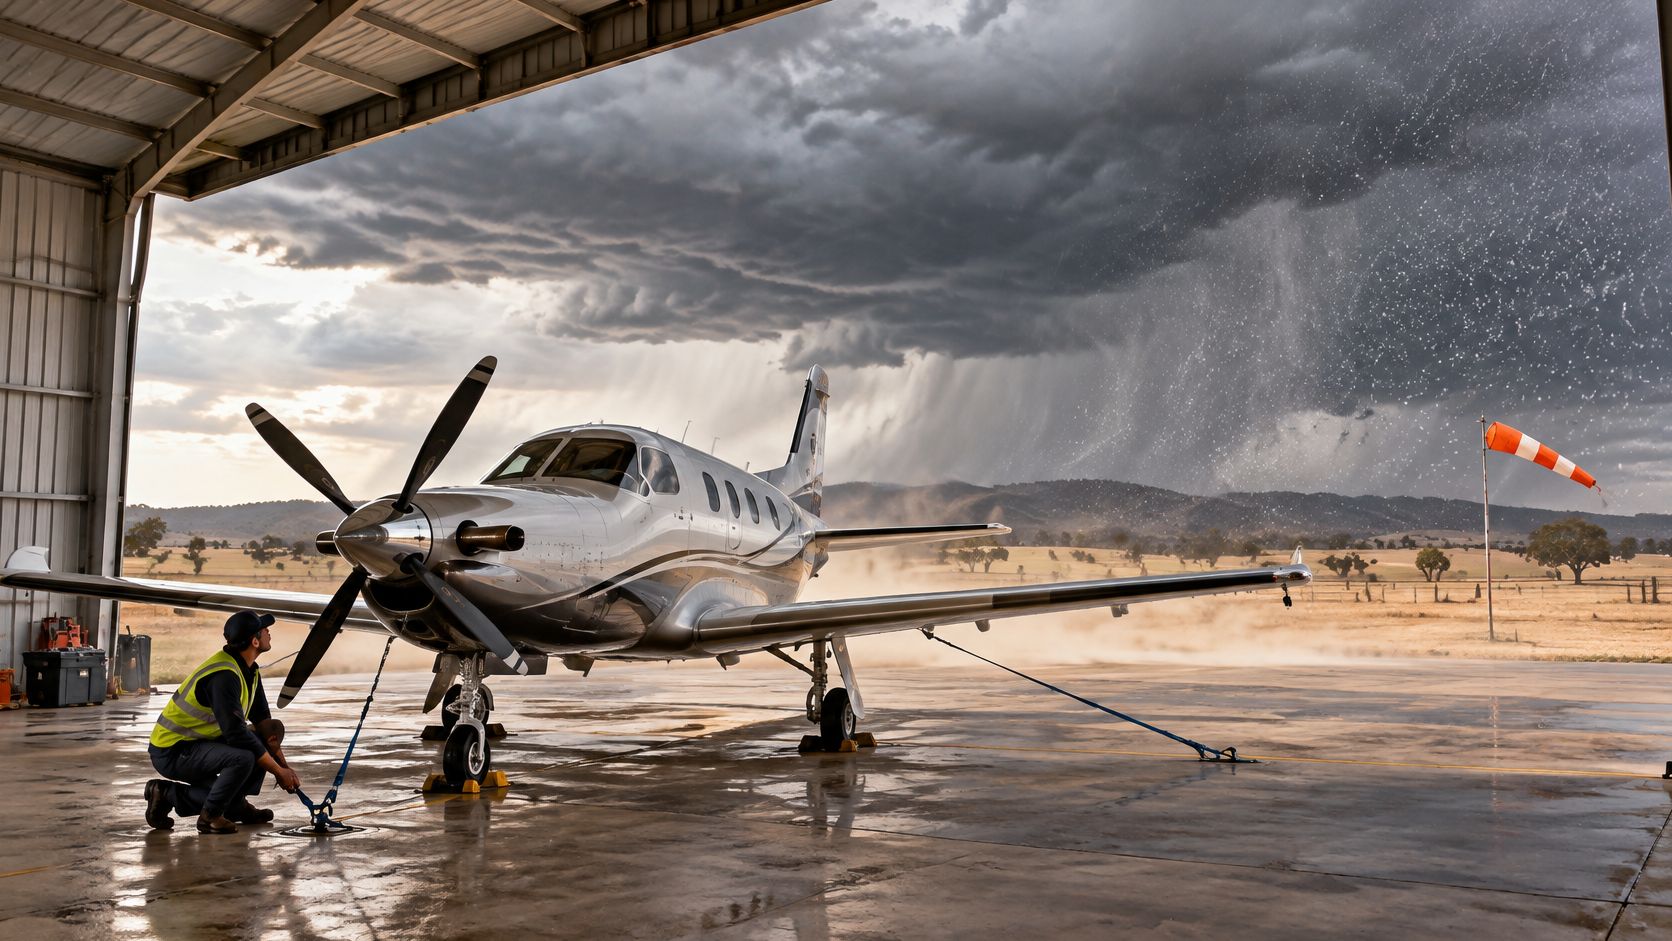
Engineers Australia's Supporting Australia's Aviation Transformation report identifies aviation infrastructure exposure to wind, turbulence, dust, smoke, hail, flooding and extreme temperatures. For owners based regionally or on private property, the practical question is how the insurance responds at that particular location.
Separate damage from disruption
Ask whether the wording addresses:
- Preventative relocation: Moving the aircraft before a forecast event, including approval requirements.
- Temporary hangarage: Accommodation away from the usual base and any reimbursement conditions.
- Inspection expenses: Contamination or corrosion checks following smoke or flood exposure.
- Loss of use: Inability to operate while an airport is inaccessible, including whether physical damage is required.
- Remote recovery: Retrieval, dismantling and transport from an isolated strip.
None of these should be assumed merely because weather damage is insured. In particular, cover for physical loss doesn't necessarily reimburse the cost of inconvenience, replacement transport or airport closure.
Check the expense provisions
Read sub-limits and excesses alongside salvage, transit and emergency ferry provisions. Establish whether recovery expenses sit within the hull amount or are payable in addition, and how the agreed-value settlement provisions interact with those costs.
Check conditions concerning hangar security, tie-downs and storm preparation. Obtain consent before committing to non-emergency recovery expenditure where the wording requires it, while prioritising safety and preventing further damage.
Location check: Describe where the aircraft actually spends the night, including seasonal trips and private strips, not just its postal home base.
For the grass-strip aircraft, a rushed departure after flood exposure could create a separate liability problem involving passengers or other property. Insurance approval isn't an airworthiness assessment or permission to use a damaged runway.
Put these questions in writing: Which relocation expenses are covered? What pays for inspection and recovery? What protection applies if the aircraft is undamaged but can't be used?
How to Arrange Private Aircraft Cover in Australia
Prepare the submission before requesting a price. A clear description lets insurers assess the same operation and reduces the risk of comparing quotations based on different assumptions.
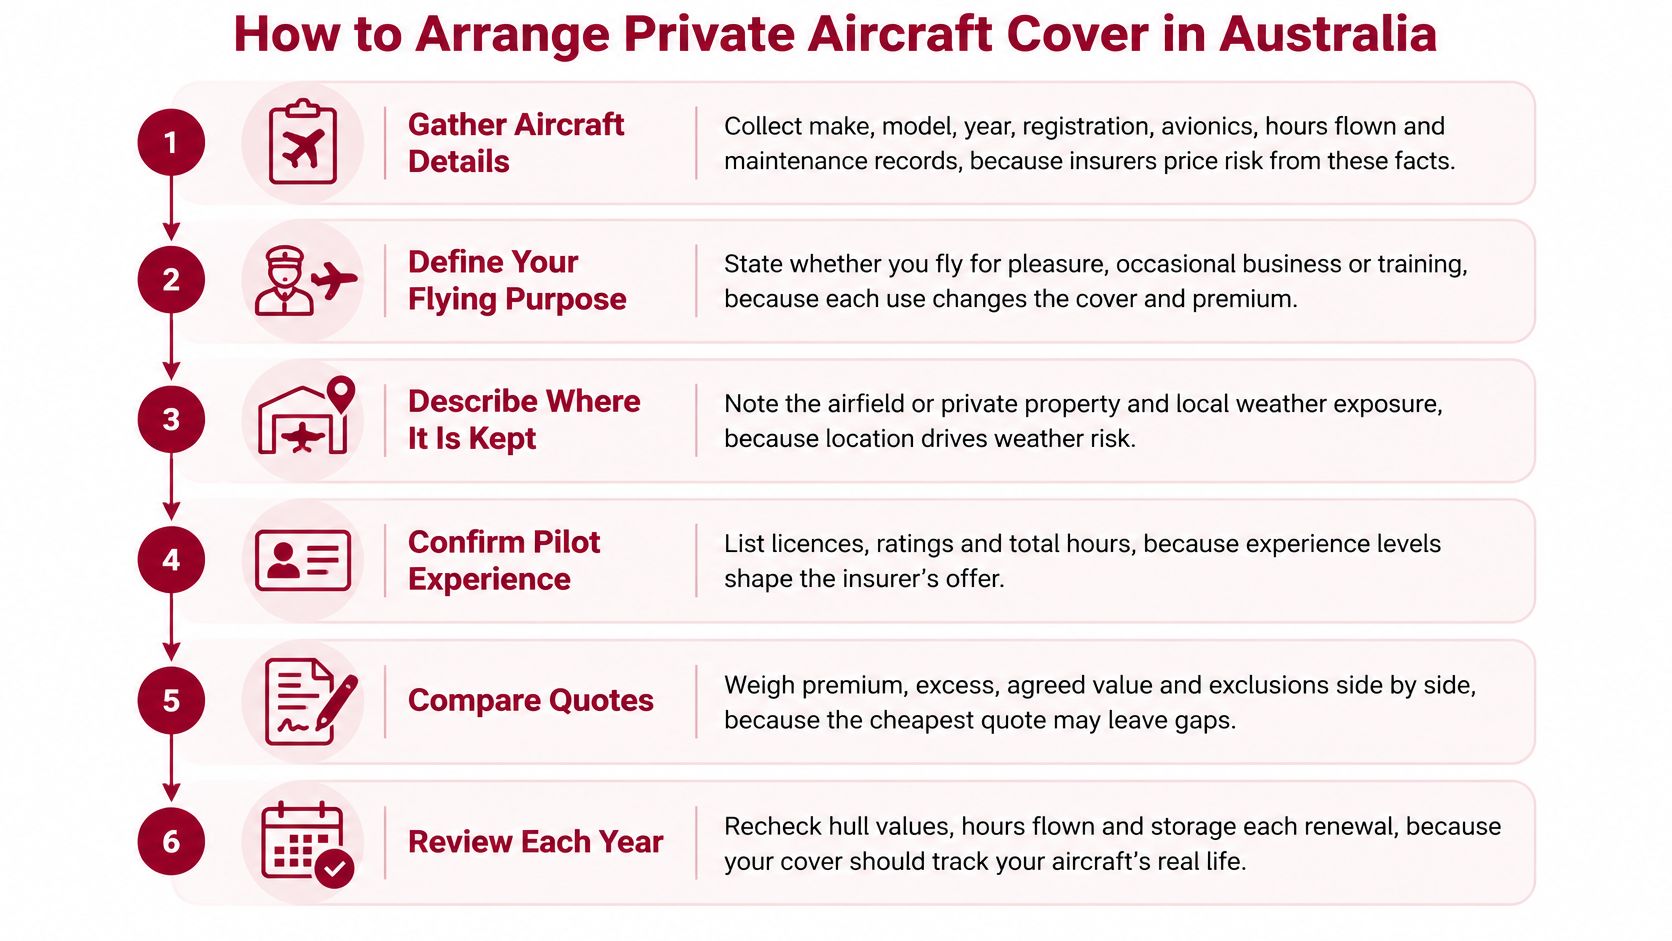
Build the submission and compare the offer
Gather aircraft details. Collect make, model, year, registration, avionics, aircraft hours and maintenance records. Include ownership details and storage arrangements so the submission describes the asset and who has an interest in it.
Define the operation. List every purpose, proposed pilot, passenger category and expected annual flying hours. Explain mixed-use activities in ordinary language rather than choosing a private-use label and leaving the insurer to infer the rest.
Establish the insured value. Use a current valuation supported by the aircraft's condition, equipment and relevant market information, rather than relying solely on an old purchase price. Confirm what evidence the insurer needs to accept the proposed amount.
Choose the protection. Specify the required hull scope, legal liability limit, passenger protection and any non-ownership exposure. Add recovery and location-related requests expressly, so an omitted extension isn't mistaken for an included benefit.
Compare equivalent quotations. Request the full wording and align limits, excesses, sub-limits and exclusions before judging premium. Identify any outstanding information or conditions that prevent the quoted terms from being final.
Test the pilot and use clauses. Read the proposed conditions against the people and missions you've declared. Ask for discrepancies to be corrected in the documents, rather than relying on a conversation that the aircraft should be fine.
Bind and record acceptance. Obtain written confirmation of the commencement date, time and any conditions that must be satisfied. A quotation isn't confirmation that insurance has started.
Schedule the next review. Diarise renewal preparation and notify operational changes before undertaking the changed activity. Use an aircraft insurance renewal checklist to keep valuations, pilot records and operating details current.
Keep a complete binding file
Retain the signed schedule, declared usage, accepted pilot list and excess in writing, together with the wording, endorsements and binding confirmation. Keep the insurer's responses to unusual operations with those documents, not scattered across messages that are difficult to retrieve.
At ABS Insurance Brokers Pty Ltd, our process is Tell Us What You Need, Risk Assessment, Compare Cover Options, and Arrange Your Cover. We provide access to Australia's leading insurers, helping owners present their requirements and compare the terms offered.
The useful outcome isn't a certificate. It's a documented agreement that accurately describes the aircraft, operation and protection you've selected.
Arrange Your Cover Review at Bankstown Aerodrome
Review your cover before your next flight, particularly if the intended operation differs from the one you last declared. Resolve uncertain permissions while you can still change the arrangements, rather than after an incident.
ABS Insurance Brokers Pty Ltd is a Bankstown Aerodrome-based brokerage and a leading supplier of aviation insurance. Our published office details list the Sydney office at 2 Hartzell Place, Bankstown Aerodrome, NSW 2200, with weekday hours of 8:00 am to 5:00 pm and the national contact number 1300 871 318.
Bring the operation, not just the renewal notice
We arrange aviation insurance across Australia for aircraft owners, pilots, operators and airport-based businesses. The offering includes aircraft hull and liability, non-ownership liability, hangarkeepers liability, aerial-application liability, drone insurance, and specialist protection for ground handlers and refuellers.
We hold Australian Financial Services Licence No. 700333, and a free insurance quote is available on request. Any proposed protection still needs to be assessed against the relevant insurer's terms.
Before calling, complete these checks:
- Gather the aircraft file: Include registration, equipment, maintenance information, valuation support and pilot records.
- Write out the usage: Describe ordinary flights and occasional exceptions, including business tasks, contributions and hired pilots.
- Request written terms: Ask for exclusions, sub-limits and answers to your location-specific questions before binding.
Give the review enough detail to address your actual decisions. A planned change of base, a new pilot or an unusual mission is more useful to discuss than a general request to renew everything unchanged.
ABS Insurance Brokers Pty Ltd offers private aircraft insurance advice and placement to help align hull, liability and specialist protection with your aircraft's real operation. Visit ABS Insurance Brokers Pty Ltd to request a free quote and arrange a review of your pilots, permitted use and storage exposures before your next flight.