You've got the plans, a start date, and trades who want a deposit before they roll onto the site. The question that usually lands last is the one that decides whether a storm, a leak or a neighbour's damaged fence comes out of your pocket. Owner builder insurance Australia for a build you're still arranging into 2027 is not one policy you tick off. It's a set of covers that only respond when the contracts, the certificates and the sum insured match who is doing the work.
Most guides treat this as a shopping exercise. Buy a construction policy, file the PDF, and get on with the slab. That fails when the loss is defective work rather than a fallen wall, or when one trade's contract sits over a statutory line and another's doesn't. I would treat the paperwork as part of the build program, not an admin task you finish after the first invoice.
The decisions below are the ones that matter before anyone is paid: which state rule applies, which contract needs statutory cover, which policy answers which loss, and what a headline limit will not pay.
Table of Contents
- Owner Builder Rules in Each State and Territory
- When Owner Builders Must Insure the Work
- Policy Types Compared Side by Side
- Defects, Workmanship and What Insurance Leaves Out
- Setting the Limit, Premium Drivers and Arranging Cover
- Common Pitfalls and Questions Before Work Starts
Owner Builder Rules in Each State and Territory
The same house project can trigger different approval and contract rules in Newcastle and Brisbane. The regulator and requirements change by state, so identify the applicable rule before finalising the build arrangements.
| State or territory | Regulator | Owner builder rule |
|---|---|---|
| NSW | NSW Fair Trading | Owner-builder warning and permit thresholds |
| QLD | Queensland Building and Construction Commission (QBCC) | Owner-builder permit thresholds |
| VIC | Victorian Building Authority (VBA) | Owner-builder registration for domestic work |
| WA | Building and Energy, Department of Mines, Industry Regulation and Safety | Owner-builder approval |
| SA | Consumer and Business Services | Owner-builder approval and licensing requirements |
| TAS | Consumer, Building and Occupational Services | Owner-builder permit requirements |
| ACT | Access Canberra | Owner-builder licence requirements |
| NT | Northern Territory Building Practitioners Board | Owner-builder registration and building permit requirements |
NSW has specific scheme figures. The NSW Home Building Regulation 2014 sets a $20,000 inclusive-of-GST threshold for the warning that applies where owner-builder work is uninsured, and for specified HBCF insurance thresholds. It also sets minimum construction-period insurance of $340,000 for each dwelling covered and a maximum excess of $250.
These are statutory scheme parameters, not a project-specific sum insured. Check how your contracts and policy address the work, liability and materials before relying on a headline limit.
Queensland has its own settings. For the Brisbane project, read the owner builder insurance requirements in Queensland and confirm the permit threshold with the QBCC. In Victoria, Western Australia, South Australia, Tasmania, the ACT and the Northern Territory, check the relevant regulator's approval, registration or licence requirements against your project. Keep the regulator's guidance with your build documents and recheck it if the project arrangements change.
When Owner Builders Must Insure the Work
A slab, electrical and plumbing job can sit under three separate contracts. Each needs its own check: owner-builder rules apply to your project, while insurance requirements for contractors depend on the state and the contract.
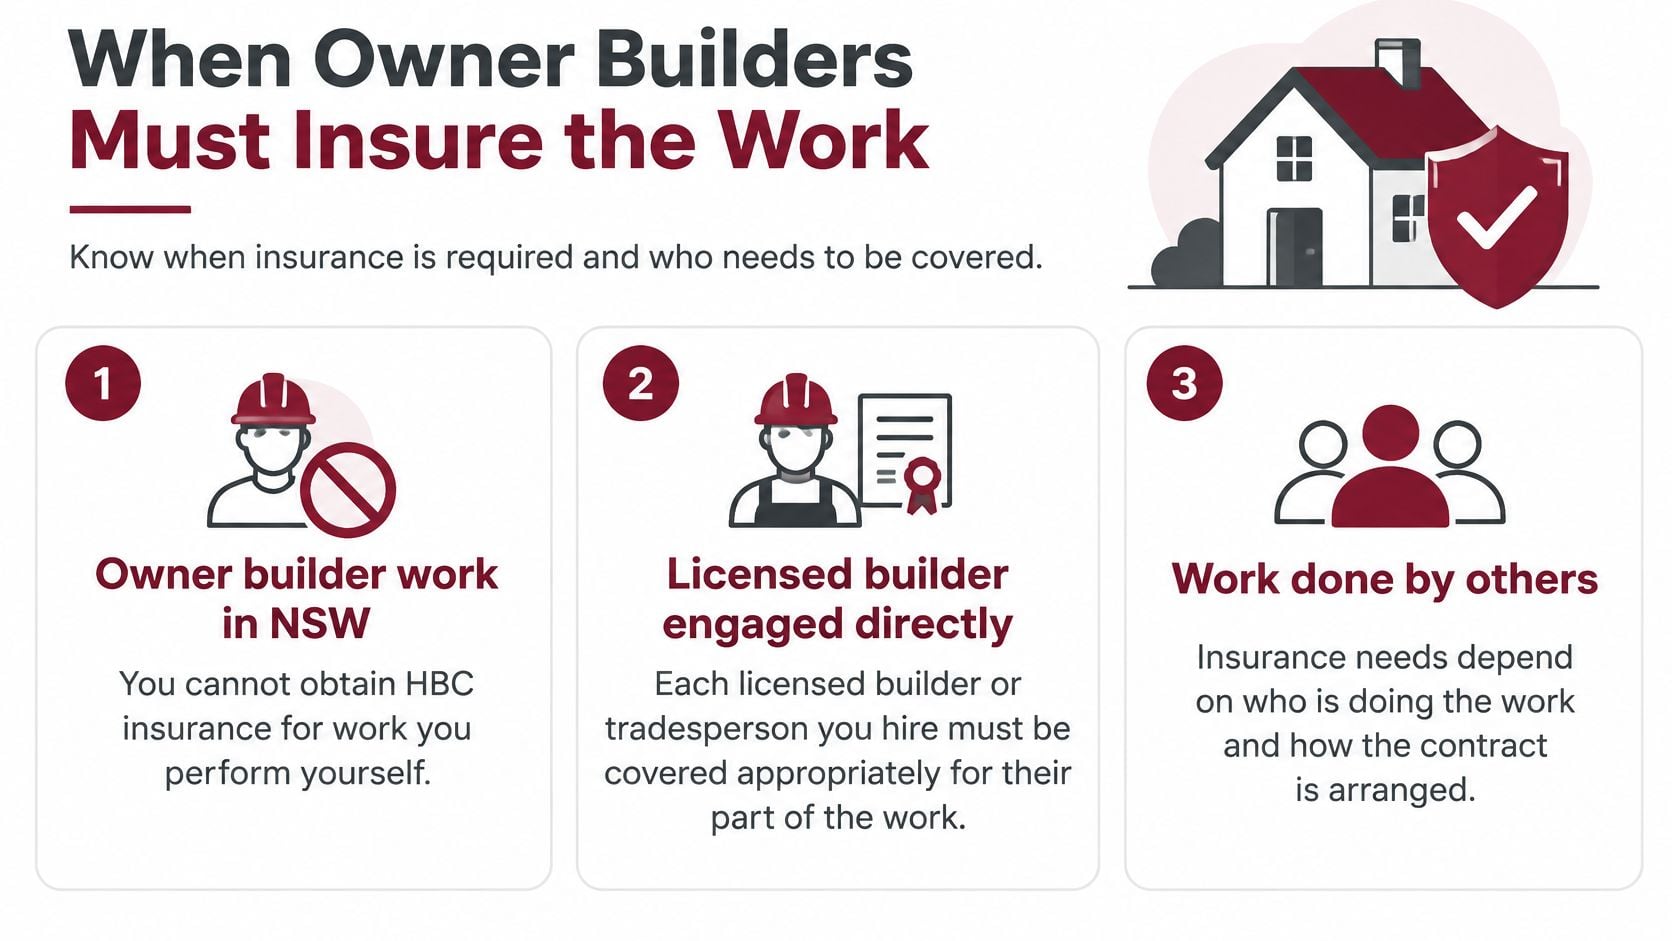
In NSW, you can't obtain HBC insurance for work you perform yourself. Each licensed builder or tradesperson you engage directly must generally provide HBC cover when their contract price exceeds AUD 20,000, including materials they supply, according to the NSW owner-builder guidance on working with contractors. Get the certificate before work starts and before you pay.
A three-contract test
Suppose the slab contract is $28,000, the electrical contract is $14,000 and the plumbing contract is $22,000. The slab and plumbing contracts each cross the threshold; the electrical contract does not. Apply the same separate check to roofing, framing and fit-out. A certificate for one contract does not cover another trade you hired under separate paperwork.
Outside NSW, check the regulator's rules for owner-builder work and the insurance requirements for contractors. Victoria's requirements are described in this guide to domestic building insurance under Victoria's scheme.
Before the first deposit:
- List every direct contract: put the slab, frame, roof, plumbing, electrical and fit-out on separate lines.
- Record each price: include materials supplied by that contractor.
- Mark the threshold: identify which contracts pass the applicable test.
- File each certificate: match it to the contractor and scope before paying.
Public liability for your own presence on site may be worth arranging even where it isn't compulsory. Hiring a licensed builder instead shifts some contract and defect responsibilities to that builder's policies and, in NSW, to HBCF. A hybrid arrangement lets you retain some trades while a builder takes on others, but you remain responsible for coordinating every contract you sign.
Policy Types Compared Side by Side
Owner builder cover is a set of policies that answer different losses. Buying the one with the largest sum insured doesn't fill the gaps in the others.
| Cover | What it responds to | Common exclusions | Usually needed when |
|---|---|---|---|
| Contract works insurance | Loss or damage to the works, materials and temporary structures during construction | Defective workmanship itself, normal wear | The build is underway and materials are on site |
| Public liability | Injury or property damage to third parties | The owner's own workers' injury, contractual liability | Anyone other than the owner accesses the site |
| Home building compensation (NSW) | Defects by eligible licensed contractors when statutory conditions are met | The owner builder's own work | A contractor's contract price exceeds $20,000 |
| Home warranty or builders warranty (other states) | Defects by eligible contractors where that state's scheme applies | The owner builder's own labour, and losses outside the scheme's defect list | That state's scheme applies to the contractor's contract |
| Theft and plant cover | Stolen or damaged tools, equipment and materials | Unsecured tools, and hired plant insured only on the hire contract | Materials or plant are stored on site |
A storm shows the split
A storm hits a half-framed house overnight. Framing is twisted, stored cladding is soaked, and a sheet of plywood lands on the neighbour's fence. Contract works is the cover aimed at the frame, the cladding and temporary structures. Public liability is the cover aimed at the fence, because that's someone else's property. Neither policy's job is to rebuild a wall that was badly built and then failed in calm weather. Normal wear, injury to people you employ (that sits with other schemes), and liabilities you accepted in a contract are the usual carve-outs across this set.
No single policy covers the whole build. Map each phase, from site set-up to lock-up to fit-out, against the table and confirm which cover is live for that stage.
Theft and plant only helps if the schedule lists what's on site and the storage condition in the wording is met. Statutory defect cover, where it exists, follows the licensed contractor's eligibility, not the fact that you paid for a construction policy.
Defects, Workmanship and What Insurance Leaves Out
Buying a policy doesn't mean the cost of correcting poor workmanship is insured. The wording, the cause of loss and the line between the defect and the damage it causes matter more than the headline sum insured.
NSW's 2025 strata-defects research, set out by the NSW Government, found serious defects in 53% of surveyed buildings. Waterproofing was the most prevalent category at 22%, followed by fire-safety defects at 16%. Only 36% of buildings with serious defects had been reported to the regulator. Those figures describe strata buildings, not owner-builder claims. Use them as context for how often serious defects stay private, not as a measure of how often a policy pays.
What to do when the work fails
- Photograph it dated. Wide shots and close-ups, before anyone "makes good" the area.
- Classify the loss. Physical damage, rectification of defective workmanship, consequential damage, or third-party liability. A failed membrane is not the same claim as the ceiling it ruined.
- Notify the relevant insurer promptly. Late notice is a common reason a response stalls.
- Keep your recovery path. Don't sign a release with the contractor while an insurer is still asking who is responsible.
If a tree is part of the cause, Treecorp Solutions advice on storm damage is a useful way to separate the physical event from a workmanship argument before you lodge. Who pays for a building defect more broadly is covered in this guide to building defects insurance in Australia.
The file that decides the claim is boring and specific: signed contracts, licence and insurance certificates, invoices, inspection records, photographs and the subcontractor's insurance details. Negotiation is often the first stop. Plenty of disputes still move to a tribunal or a regulator, so that folder has to exist from day one, not the week a purchaser or a lender asks questions.
Setting the Limit, Premium Drivers and Arranging Cover
The sum insured should reflect what it would cost to reinstate the works, not the budget you first wrote down. A rebuild estimate includes demolition, temporary accommodation, engineering, design changes, compliance work, waste removal and professional fees. Replacement materials are only one line.
Price the rebuild, not the quote
Picture a house at lock-up stage. Market value might describe what a buyer would pay for the block with a half-finished building on it. Reinstatement is the cost of clearing damaged work and bringing the project back to the same stage, under current prices, with fees included. Insuring the original budget leaves that gap with you.
Some losses sit outside a normal construction wording even when the limit looks generous. Contractual penalties for late completion, deliberate non-compliance, and some forms of defective workmanship are the gaps I would name in writing before you bind. If a quote is silent on one of those, ask. Silence isn't cover.
What insurers actually price
Premiums move too widely by state, site and build to quote one national range. Read every quote for the sum insured, the excess, the exclusions, GST and any broker or insurer fee, and only compare quotes written on the same scope.
| Factor | Why it moves the premium | Evidence to prepare |
|---|---|---|
| Build value and rebuild cost | Higher limits mean higher premiums | A builder's or quantity surveyor's rebuild estimate |
| Build duration | Longer exposure to weather, theft and delay | A construction program with milestones |
| Site location and hazards | Flood, bushfire, coastal or slope exposure raises risk | The site address and hazard mapping |
| Construction method and materials | Some methods and materials carry higher damage risk | Plans and material specifications |
| Number of trades and subcontractors | More parties increase liability and defect exposure | Subcontractor licences and insurance certificates |
| Claims history | Prior claims can raise the rate or limit who will quote | Claims history for the owner and any builder involved |
A cheap premium on a short period and a low limit is not a saving if the first variation blows both.
Seven steps before the first deposit
- Confirm the regulator and the owner builder rule for your state or territory, using the row that matches the build. A policy can't fix a permit you weren't eligible to hold.
- List every contract with its value. Each direct contract is assessed on its own. Don't assume one project certificate covers every trade, including for a start you're still planning into 2027.
- Get a rebuild estimate and a construction program so the limit and the policy period match the job, not the sales brochure.
- Collect each contractor's licence and insurance certificate and check the certificate describes the actual scope. For NSW residential building work by a contractor, the NSW contracts guidance states that the $20,000 HBCF threshold is inclusive of GST, and that where the contract price is unknown the test is whether the reasonable market cost of the labour and materials exceeds $20,000. It is illegal for a contractor to request a deposit or other payment for covered work until the required insurance has been taken out and the certificate provided. Check that certificate before you pay anything.
- Ask at least two insurers, or a broker, to quote the same scope. Compare exclusions and excesses, not just the premium.
- Match the cover start date to the first day on site, including delivery of materials, not the day the frame stands up.
- Keep every certificate, invoice and variation in one folder. A claim handler will ask for the version of the contract that was current when the loss happened.
Do step 4 even when you trust the trade. A certificate that names a different address, an expired period or a scope that stops at "labour only" won't carry a materials-heavy contract.
Common Pitfalls and Questions Before Work Starts
Insurance gaps often appear between policies, contracts and trade documents. A public liability policy addresses third-party injury or property damage; it does not insure the building work itself. Check separately whether contract works, theft and any state-required cover apply to your project.
Does one certificate cover every trade? No. Check each contractor's certificate against their own contract and scope. A roofer's certificate does not confirm that an electrician is insured for electrical work.
Should I insure for the original budget? Use the rebuild estimate, then review the limit when variations change the project. A new storey or different cladding can alter the amount at risk. The policy limit matters, but it does not make defective workmanship covered.
What if a subcontractor's cover lapses mid-build? If the contract requires current insurance, pause payment until you have a current certificate and record the lapse date. For electrical work, check the contractor's licence and insurance certificate together before the rough-in, confirm both match the scope in writing, and keep copies in the project folder. A homeowner's guide to safe electrical hiring is a useful starting point for that check.
Can the policy start after the first materials arrive? The start date should cover the first day on site and the arrival of materials. If materials are left on site before cover begins, they may be exposed to loss without insurance.
Who can help place it? ABS Insurance Brokers Pty Ltd arranges owner builder insurance and can advise on contract works, liability and related project cover, as well as building consultancy support linked to insurance needs. Contact the brokerage through abshow.com.au before work begins, and confirm the policy's scope and exclusions with the insurer. A quote alone does not guarantee a claim will be paid.
ABS Insurance Brokers Pty Ltd places owner builder insurance for Australians managing new homes, renovations and extensions. The practical task is to line up the policy with the contracts, trade scopes, limit and start date. Visit ABS Insurance Brokers Pty Ltd to discuss cover for your state, trades and construction program.