Excavation contractors need a layered insurance programme that goes beyond standard public liability. Core covers include public liability with XCU endorsements, plant and equipment (inland marine), workers' compensation, and environmental liability. Without specific cover for underground hazards, a standard policy can exclude the most common excavation claims: underground utility strikes, trench collapse, and explosion damage. This article explains what each layer covers and what the key exclusions are for the risks excavation work actually produces.
Why Excavation Work Carries a Unique Risk Profile
Excavation contracting sits in a different risk category to most construction trades. The work involves breaking ground in environments where hazards are invisible, unpredictable, and capable of causing serious harm to people, property, and the surrounding environment, often all at once.
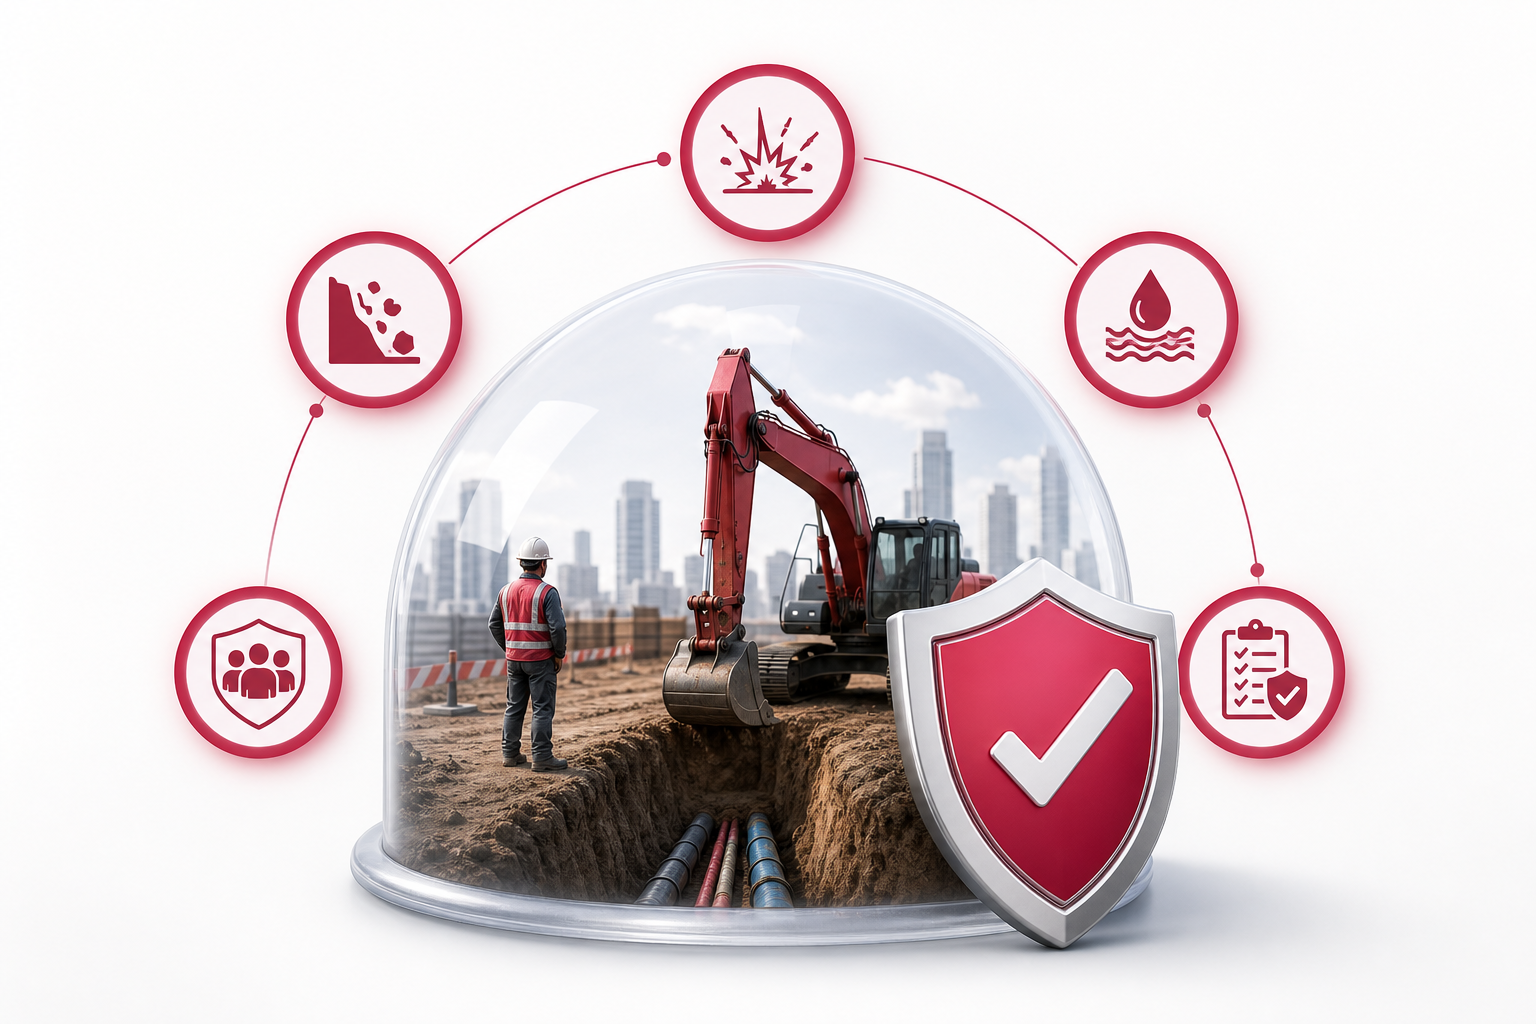
Four hazard categories set excavation apart from general construction work.
Underground utilities are the most frequent source of third-party claims. Gas mains, water pipes, electrical cables, and fibre optic infrastructure run through almost every urban and suburban site. A single misidentified line can cause an explosion, a major outage, or significant damage to a neighbouring property.
Trench collapse is the most serious risk to workers. Unsupported excavations can fail without warning, particularly in wet or sandy soils. The consequences are severe, and the frequency of injury claims reflects that. According to Dataintelo's 2025 research, workers' compensation claims for excavation work run 15 to 18 per cent higher on average than claims in general construction. That figure comes from global data and should be read as directional context rather than an Australian benchmark, but the underlying pattern is consistent with the nature of the work. Heavy plant introduces both asset and liability exposure. Excavators, bobcats, and tip trucks are expensive to repair or replace, and they can cause substantial damage if they malfunction or are operated incorrectly near structures or the public.
Environmental contamination is a growing concern, particularly on brownfield sites or near waterways. Diesel spills, disturbed asbestos, and contaminated soil movement can trigger regulatory action and third-party claims that a standard public liability policy may not cover.
Each of these categories requires a specific policy response. A programme built only around standard public liability leaves gaps that can be costly to discover after a claim is lodged.
What Is XCU Coverage and Why Standard Policies Exclude It?
XCU is a term used in insurance to describe three specific hazard categories: Explosion, Collapse, and Underground damage. In Australian policy documents, you may see these risks described differently, as specific exclusions for underground property damage, subsidence, or vibration-related loss, but the underlying concept is the same. Standard contractor liability policies commonly exclude one or more of these hazards.
Insurers apply these exclusions because excavation-related claims in these categories tend to be severe and difficult to predict. A utility strike that ignites a gas main, a trench wall that collapses into a neighbouring building's foundations, vibration from heavy equipment that shifts underground infrastructure: none of these are low-frequency, low-cost events. Insurers price standard policies without them and require contractors to specifically request their reinstatement.
The practical consequence for you is significant. If your public liability policy contains an underground damage exclusion and your excavator strikes a fibre optic cable, the insurer may decline the claim entirely. The same applies if vibration from your equipment causes a nearby structure to crack or settle. You may believe you are covered, lodge a claim, and find the policy does not respond.
Reinstating this cover requires an endorsement, sometimes called a removal of exclusion endorsement, added to your public liability policy at the time of placement. Not all insurers offer this for excavation contractors, which is one reason why specialist placement matters.
There are a few practical points to confirm when arranging cover:
- Check whether your policy excludes underground property damage, subsidence, vibration, or collapse specifically, not just in the general exclusions schedule.
- Confirm whether the endorsement covers third-party property damage only, or also bodily injury arising from the same events.
- Ask whether the endorsement applies to your owned plant and equipment or only to third-party losses. These are separate policy sections.
- Verify that the reinstated cover extends to utility strikes, including telecommunications infrastructure, not just gas and water.
If your broker cannot confirm these points in writing, the policy wording itself is the only reliable reference. Do not assume cover exists because it was not explicitly excluded in a conversation.
Which Excavation Contractor Insurance Policies Do You Actually Need?
A well-designed programme for an excavation contractor typically includes five policy layers. Each covers a distinct exposure, and none replaces the others.
1. Public Liability Insurance
Public liability covers your legal liability for bodily injury or property damage caused to third parties during your operations. For excavation contractors, this is the foundation of any programme, but it must include the underground hazard endorsements described above. Standard limits in the Australian construction market start at $5 million, though many contracts and principal contractors require $10 million or $20 million. These figures reflect common contract requirements rather than a published industry benchmark. Check your contract documents and any licensing conditions in your state to confirm the minimum limit required for your work. For guidance on selecting the right limit relative to your contract size, see Public Liability Insurance for Builders: Getting the Right Limit for Your Contract Size.
2. Plant and Equipment Insurance (Inland Marine)
Your excavators, graders, rollers, and attachments are typically not covered under a standard public liability or contract works policy while in transit or stored off-site. Plant and equipment insurance, sometimes called mobile plant insurance or inland marine cover in international contexts, covers physical loss or damage to your owned or hired-in machinery. Confirm whether your policy covers hired-in plant. Many smaller operators rely on short-term hire and assume the hire company's insurance is sufficient. It generally is not.
3. Workers' Compensation
Workers' compensation is compulsory for all employers in Australia, and the requirements vary by state. If you employ workers on excavation sites, you must hold a current workers' compensation policy in the relevant jurisdiction. The elevated injury rate in excavation work makes this a high-exposure line; do not treat it as a formality.
4. Professional Indemnity Insurance for Trades
Professional indemnity insurance for trades applies when you provide advice, design input, or survey-related services alongside your physical work. If you advise a client on excavation depth, soil classification, or site preparation and that advice contributes to a loss, a public liability policy will not respond, professional indemnity will. This cover is increasingly relevant as excavation contractors take on more complex projects where design-and-construct elements are included in the scope.
5. Environmental and Pollution Liability
Environmental liability covers the costs of cleaning up contamination and responding to third-party claims arising from pollution events during your work. Diesel spills, disturbed contaminated soil, and sediment runoff into waterways are all plausible excavation scenarios. Standard public liability policies typically exclude gradual pollution events. A standalone environmental liability policy, or a pollution liability extension, fills that gap.
Licensing, Bonds, and State Requirements for Excavation Contractors in Australia
Licensing and bonding requirements for excavation contractors vary significantly across Australian states, and the insurance obligations attached to those licences are not uniform. Understanding what applies in your jurisdiction is essential before you price a job or sign a contract.
In New South Wales, excavation work above certain thresholds requires a contractor licence issued by NSW Fair Trading. Excavation contractor insurance in NSW must typically satisfy the minimum public liability requirements set by the licencing authority, and some contracts with councils or government principals specify higher limits. Contractors working near existing structures or on complex urban sites face additional scrutiny, and insurers may require site-specific risk information before confirming terms.
In Western Australia, the Building Services Board regulates contractors, and public liability insurance is a condition of registration. Public liability insurance in WA must generally be maintained for the duration of any registered contractor's licence. The minimum required limit can differ from what a principal contractor or client specifies in a commercial contract, so always check both the regulatory floor and the contractual requirement.
In Victoria, Queensland, and South Australia, excavation-related licensing sits within broader construction or earthworks contractor categories, each with their own insurance conditions. Queensland's QBCC licensing framework, for example, requires contractors to hold public liability cover as a condition of licence, with minimum limits set by the regulator.
Licensing bonds are less common in Australia than in the United States, but some states and territories require a form of financial assurance for certain categories of earthworks or civil contracting. Where bonds are required, they sit alongside insurance rather than replacing it.
One consistent rule applies across all states: your insurance programme must be current before you start work, not arranged after the contract is signed. Retroactive cover is not available for incidents that occur before a policy is in force.
For a broader look at how public liability costs vary across Australia, the Public Liability Insurance Cost Australia: 2026 Pricing Guide covers the main pricing factors by trade and state.
How Much Does Excavation Contractor Insurance Cost?
Excavation contractor insurance costs more than cover for most other trades, and the reasons are directly tied to the risk profile described above. Premiums are driven by several factors. Understanding them helps you anticipate what insurers will ask and why.
No reliable published benchmark exists for Australian excavation insurance premiums. Excavation is a high-hazard trade, and what you pay depends on the specifics of your business, not an industry average. The main factors that move your premium are:
Annual revenue and contract size. Insurers use turnover as a proxy for exposure. A sole operator doing residential footings carries a different risk profile to a contractor running multiple machines on civil infrastructure projects. Contractors working on civil or infrastructure projects typically face higher base premiums because the potential third-party losses are larger.
Claims history. A history of utility strikes, property damage claims, or workers' compensation incidents will increase your premium and may limit the insurers willing to quote. Some insurers will decline excavation risks with recent claims entirely. Brownfield site experience and any prior pollution incidents are also scrutinised closely.
Plant and equipment value. The more machinery you own or hire, the higher the inland marine premium. Declared values must be accurate; underinsurance at claim time can result in a proportional reduction in the payout.
Cover scope. Adding underground hazard endorsements, environmental liability, and professional indemnity each adds to the total programme cost. Removing them to reduce premium is a false economy if those covers are the ones most likely to respond.
Site types and locations. Urban work near utilities, brownfield sites, and projects requiring dewatering or shoring attract higher premiums than greenfield rural excavation.
The only way to get an accurate figure is to obtain quotes based on your actual business profile.
Broker vs Direct: Which Route Gets You the Right Cover?
Two main routes exist for arranging excavation contractor insurance in Australia: a specialist broker or a direct or online placement. They suit different types of contractors, and the difference matters more for excavation than for most trades.
Direct and online insurers offer speed and convenience. For straightforward trades with standard risks, that model works well. The problem for excavation contractors is that direct platforms often cannot offer underground hazard endorsements, standalone pollution liability, or hired plant cover. Those are precisely the covers most likely to respond in a serious excavation claim.
A specialist broker can access insurers that write excavation risks, negotiate endorsements, and review policy wording for the exclusions that apply to your trade. The process takes longer and requires more documentation upfront, but the result is a programme that has been checked against your actual exposure.
If your work involves urban sites, underground utilities, hired plant, or any environmental exposure, a broker is the more appropriate route. For a detailed look at why specialist advice makes a difference on complex construction risks, see Construction Insurance Broker: Why Specialist Advice Matters.
How ABS Insurance Brokers Can Help Excavation Contractors
ABS Insurance Brokers is an Australian-owned insurance brokerage that sources and arranges specialist insurance policies for builders, construction businesses, and general commercial clients. The firm operates as part of the Steadfast Network, giving it access to a wide range of insurers and products, including those that write excavation risks with underground hazard endorsements and environmental liability extensions.
For excavation contractors, that access matters. The covers most likely to respond in a serious claim, including pollution liability, XCU-equivalent endorsements, and hired plant cover, are not available through every insurer. A broker who works regularly with construction and civil contractors can identify which markets will quote your specific risk profile and review the policy wording for the exclusions that matter most to your trade.
If you want to discuss your programme, you can reach the ABS team by phone or through an online quote request form.
FAQs
Does a standard public liability policy cover damage to underground utilities?
Not automatically. Most standard public liability policies include an exclusion for underground property damage, which can apply when your equipment strikes a gas main, water pipe, electrical cable, or telecommunications infrastructure. To be covered for these events, you need a specific endorsement that reinstates underground damage cover. Always check the exclusions schedule in your policy wording, not just the product summary, before assuming cover exists.
What filing requirements like MCS-90 apply to excavation dump trucks in Australia?
MCS-90 is a US regulatory filing requirement for commercial motor carriers and does not apply in Australia. Australian excavation contractors operating dump trucks or tip trucks need to hold a current commercial motor vehicle policy that meets the requirements of the relevant state road transport authority. Some contracts with government principals may specify minimum fleet liability limits separately from your public liability programme. Check both your contract and your state's heavy vehicle licensing conditions.
What is the difference between A-7 and A-12 licensing for insurance purposes?
A-7 and A-12 are US contractor licence classifications and are not used in Australia. Australian excavation contractors are licensed under state-based frameworks, such as NSW Fair Trading contractor licences or WA Building Services Board registration. Each state sets its own categories for earthworks and excavation work, and the insurance conditions attached to each category vary. Check with your state's licensing authority for the specific class that applies to your scope of work.
Is workers’ compensation compulsory for sole-trader excavation contractors in Australia?
Workers' compensation is compulsory for employers, meaning any business that engages workers under a contract of employment. Sole traders with no employees are generally not required to hold a workers' compensation policy for themselves, though some states allow voluntary coverage. If you engage subcontractors, the classification of those workers as employees or independent contractors affects your obligations. Requirements vary by state, so confirm the position with your state's workers' compensation authority or your broker.
Does professional indemnity insurance apply to excavation contractors who provide design or survey advice?
Yes, it can. If you provide advice on excavation depth, soil classification, site preparation, or any other technical matter that a client relies on, and that advice contributes to a loss, a public liability policy will not respond. Professional indemnity insurance for trades covers claims arising from errors or omissions in professional advice or services. The cover is relevant for excavation contractors who take on design-and-construct scopes or who advise on ground conditions as part of their service.
Conclusion
Excavation contracting carries a risk profile that standard contractor policies are not automatically designed to cover. The covers most likely to matter, underground hazard endorsements, environmental liability, and plant and equipment insurance, require deliberate selection. A standard public liability policy with a high limit is not enough on its own.
Before you arrange or renew cover, confirm that your policy addresses underground damage, that your plant values are accurately declared, and that your state-based licensing obligations are met. If your work involves urban sites, utilities, hired plant, or any environmental exposure, work with a broker who can access specialist markets and review the wording for the exclusions that apply specifically to excavation work.